

The pitch sounds almost too good: AI agents that move your money, execute stock trades, file your taxes. It's the kind of promise that makes fintech investors lean forward in their chairs.
But then you read the fine print.
Gravy's financial connections are read-only, according to terms of service the company posted. The startup "does not initiate transfers, trades, payments, or other money movement." In other words, what the marketing suggests and what the product actually does exist in different zip codes—a gap that pretty much encapsulates where agentic AI in finance stands right now. Lots of ambition. Plenty of regulatory handcuffs. And the slow, unglamorous work of building trust with people's money.
The Promise
Gravy emerged from Y Combinator's spring 2026 batch with the kind of pitch that turns heads. Two founders based in San Francisco, with a legal entity registered in the UK. They're calling their creation "agents for personal and business finances"—software that hooks into bank accounts, credit cards, brokerages. There's a Main Agent feature. A Cash Flow Operator. Tax Prep. Trading Watch. For small business owners, an Invoice Chaser that supposedly automates dunning letters to clients who haven't paid up, plus a Payroll Operator.
The privacy angle is front and center: local-only data processing on Mac desktops, nothing sent to the cloud. "Your accounts, transactions, and documents never leave your device — ever," the website declares. There's also an iOS app available in the UK App Store, priced at £7.99 monthly or £79.99 annually. As of April 2026, it had 14 ratings averaging 4.6 stars. Not a huge sample size, but respectable.
It's the kind of product that sounds perfectly timed for this moment—when every enterprise software vendor is racing to bolt AI agents onto their platforms, and venture capitalists are throwing term sheets at anything with "autonomous" in the deck.
What It Actually Does
Here's where things get more interesting, if less thrilling.
The terms of service spell it out plainly: "Gravy reads from your accounts; it never moves money on its own." The document goes on to specify that financial account connections are "intended to be read-only" unless stated otherwise in writing. And then there's this disclaimer, which probably won't end up in the marketing materials: "AI outputs need a human in the loop — Gravy isn't financial, tax, legal, or investment advice."
So what does "agents that move money, trade stocks, and file taxes" actually mean? Based on the current feature set, it appears the software is doing organizational legwork—tracking cash flow, surfacing unusual transactions, sorting tax deductions, monitoring portfolio performance. Useful, maybe. Autonomous? Not quite.
Take the Tax Prep feature. It seems designed to organize records rather than actually file returns end-to-end, a distinction that matters quite a bit when you're operating in a heavily regulated industry. One where getting things wrong can mean audits, penalties, or worse.
Under the Hood
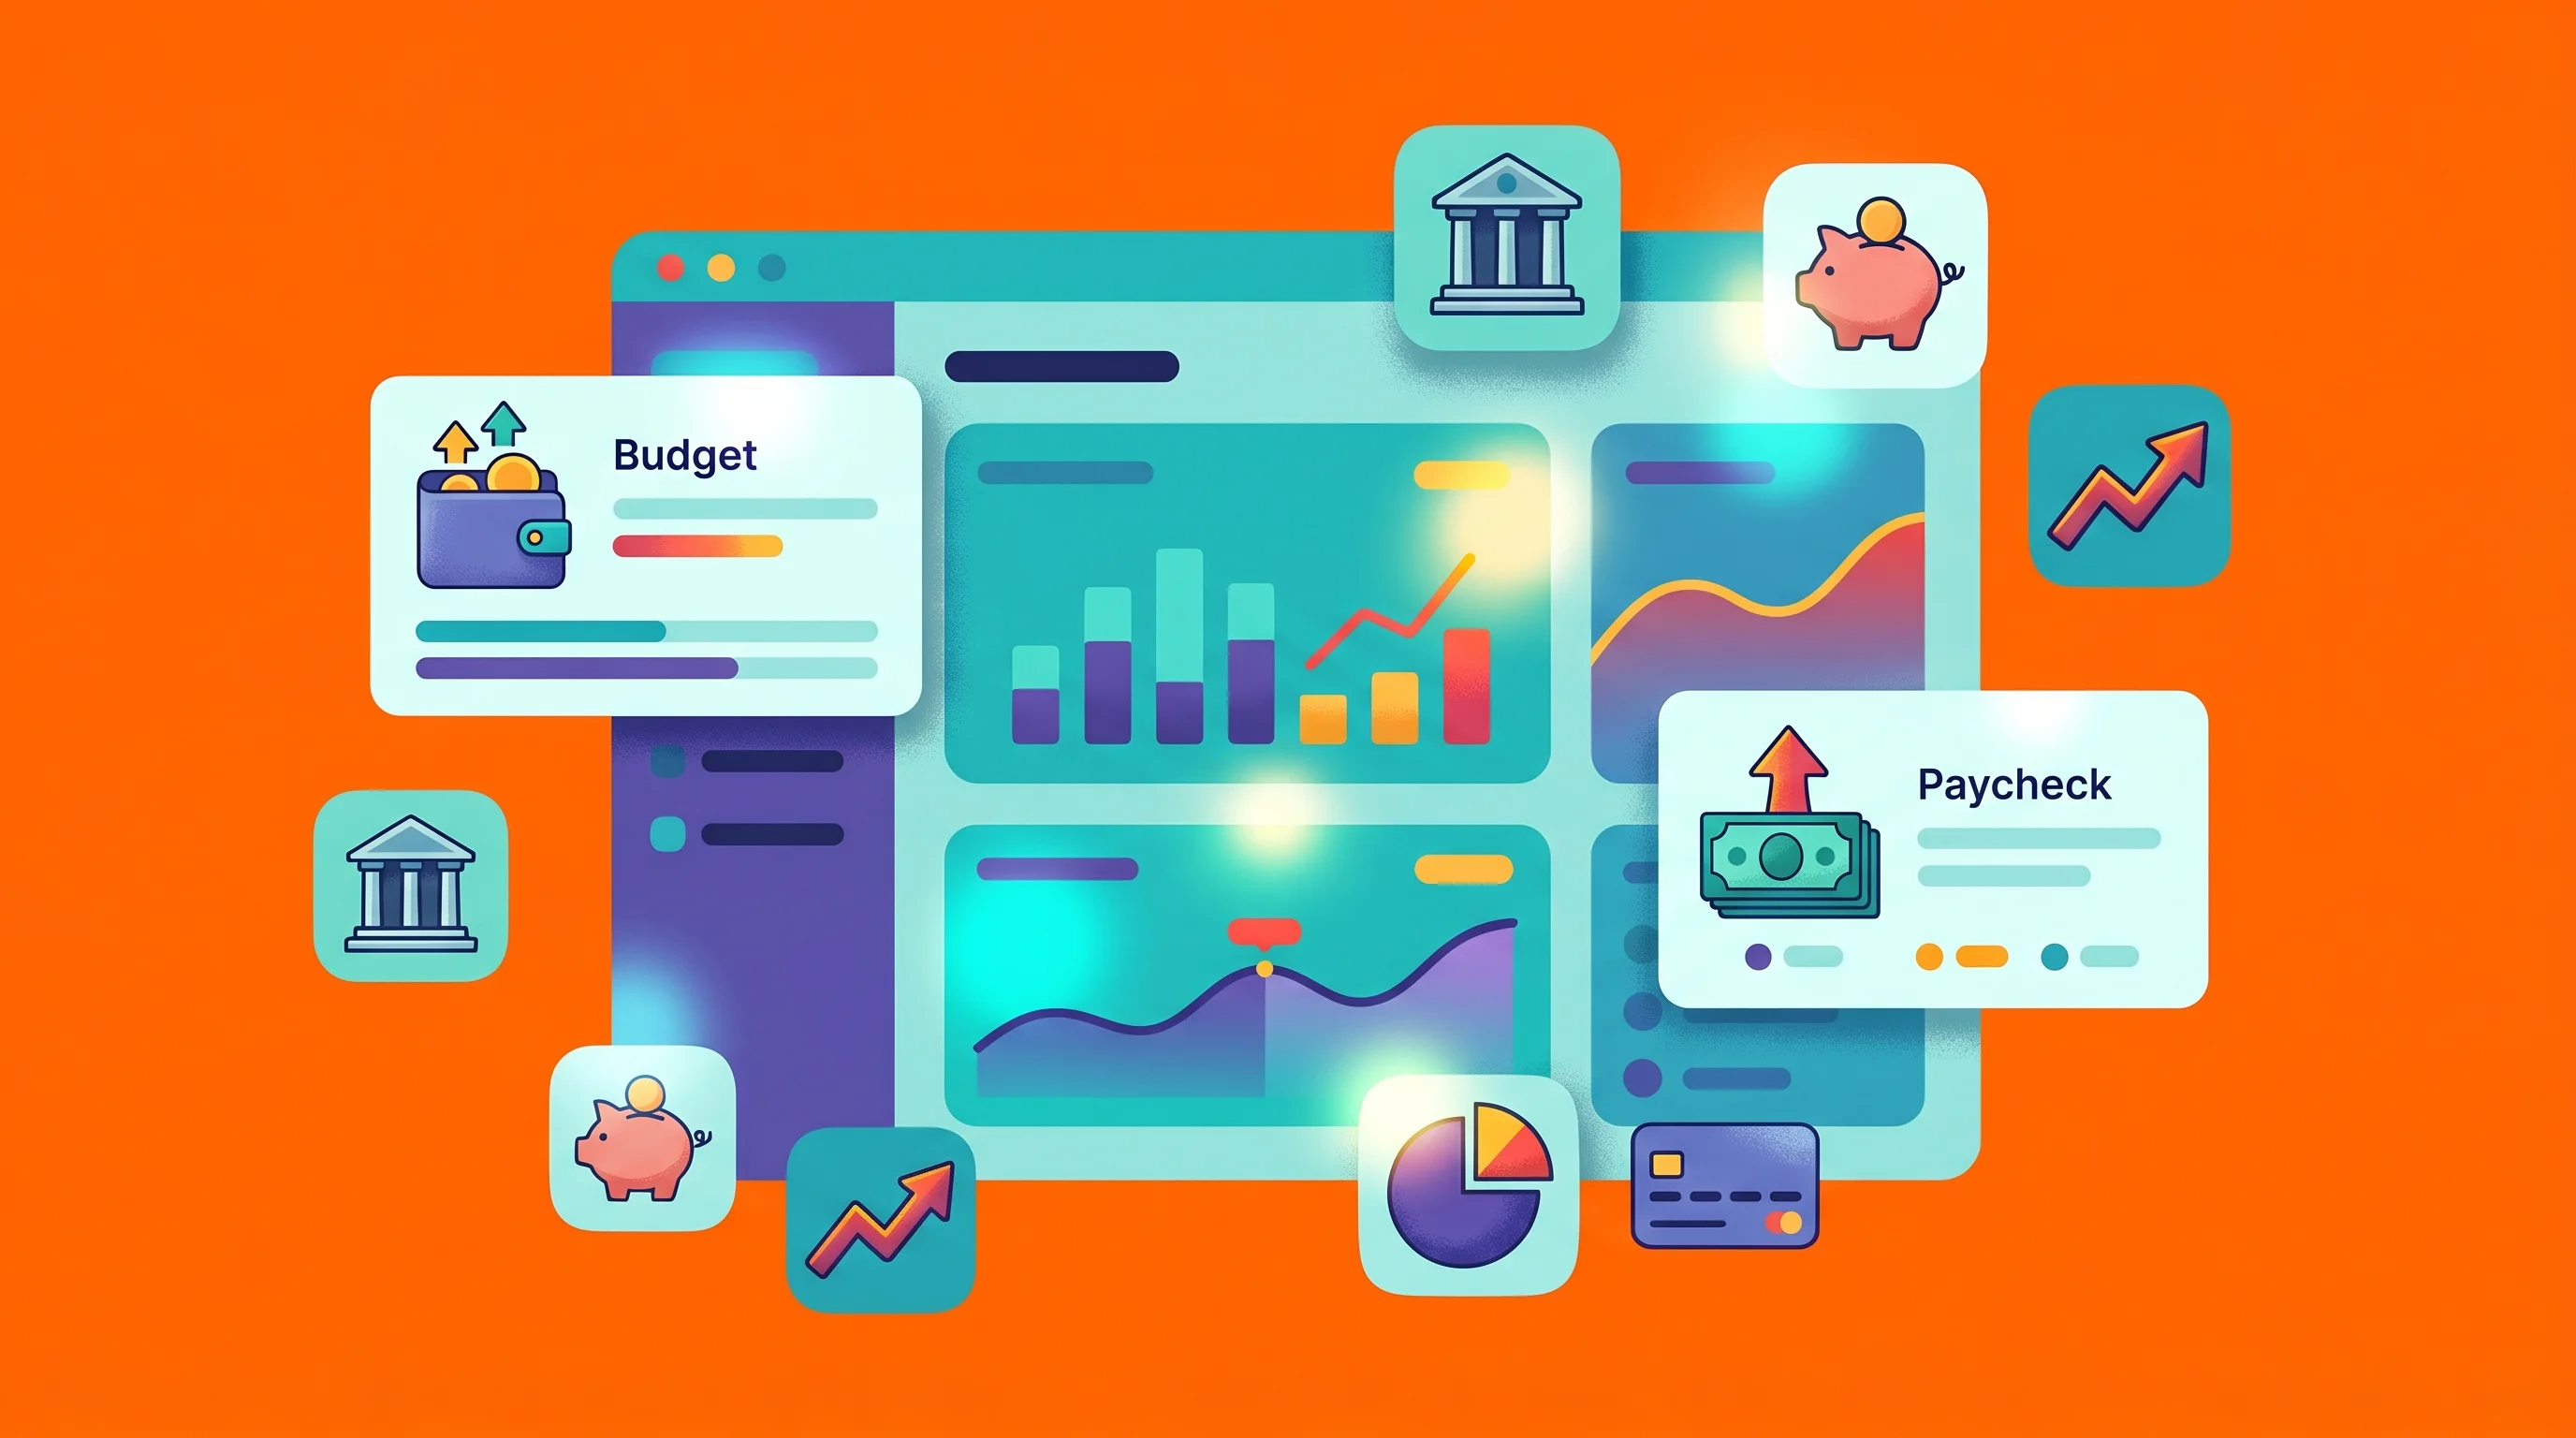
Gravy's desktop application is currently waitlist-only. The interface shows connected institutions: Chase, Wells Fargo, Robinhood. Example cards display status updates like "Your paycheck landed… update budget; flag unusual." The business version offers visibility into client payments and promises to automatically detect overdue invoices.
The privacy policy reinforces that local-first architecture. The company says it doesn't train AI models on user data, and model providers operate under enterprise contracts that forbid training or retention beyond generating immediate responses. For Gmail integration, Gravy adheres to Google's API Services User Data Policy—table stakes for anyone connecting to Google's ecosystem.
The Founders
CEO Ali Tabba's YC profile mentions he "previously co-founded KiranaKart which became Zepto" and worked in BlackRock's iShares division. CTO Max Church comes from Moonpig, where he served as lead AI engineer for a platform with over 12 million active users. It's a resume that suggests some familiarity with both consumer fintech and enterprise-scale AI deployment, though whether that translates to navigating the compliance maze of financial services remains to be seen.
The Broader Wave (and Undertow)
Gravy's launch coincides with what you might call peak hype for agentic AI in financial services. Anthropic has announced finance-focused AI agents for institutions. Fiserv launched something it calls "agentOS"—an operating system for deploying AI agents in banking, with heavy emphasis on policy controls and human oversight. Pleo introduced AI agents for autonomous spend management.
But there's an undertow. Global financial regulators have been calling for stricter controls on agentic AI. The Consumer Financial Protection Bureau has been updating its AI guidance. Fiserv's repeated emphasis on "auditability" and "human oversight" signals where compliance departments are drawing lines.
No one wants to be the company that let an AI agent drain someone's checking account because of a hallucination.
The Central Tension
Perhaps Gravy's read-only stance is deliberate positioning—a way to build trust and navigate compliance before eventually flipping the switch on real autonomous execution. Get users comfortable with AI surfacing insights, then gradually introduce features that actually move money. It's a reasonable strategy, if less exciting than the headline.
The alternative reading: the marketing got ahead of the product. Which happens. Startups live in the space between what they've built and what they promise to build, and sometimes that space gets a little wider than advisable.
Either way, Gravy illustrates the defining tension in today's agentic finance push. Everyone wants to promise the autonomous future. But for now, they're mostly delivering a supervised present, with a human required to click "confirm" before anything consequential happens.
The agents are here, technically. They're just not quite ready to move your money yet. And given what's at stake, maybe that's not such a bad thing.


