

When your AI assistant needs to actually charge your credit card mid-conversation, things get complicated fast.
Maven, a San Francisco startup that just completed Y Combinator's Winter 2026 batch, is banking on that friction. The company emerged from stealth this month with a narrow but potentially lucrative pitch: payment infrastructure purpose-built for voice AI agents that need to collect money during phone calls.
The technical challenge is real enough. Conversational AI developers face an awkward choice when their agents need to process payments. Build your own PCI-compliant infrastructure—shouldering all the regulatory overhead that implies—or break the conversation flow by texting a payment link and hoping the customer follows through. Neither option is elegant, and the second one routinely tanks conversion rates.
Maven's solution amounts to a handoff. When a voice agent hits a payment moment, it creates a session through Maven's API and transfers the caller to what the company calls a "secure collection leg." The caller punches in card details via phone keypad or gets an SMS checkout link. Transaction complete, the call automatically bounces back to the original agent. The conversation resumes.
It's the kind of unglamorous infrastructure play that doesn't make headlines but can quietly capture a market if the timing is right. And the timing, at least according to the card networks, might actually be right.
The Networks Are Ready (They Say)
Visa and Mastercard both rolled out agentic payment programs in 2025, a clear signal that they see AI-initiated commerce as more than theoretical. Visa's Intelligent Commerce sandbox went live last year. Mastercard launched Agent Pay in April 2025, complete with "agentic tokens" designed to let trusted AI systems transact autonomously.
Whether 2026 becomes "the year" for agent-driven commerce remains an open question. But the infrastructure layer is taking shape faster than most observers expected, perhaps more rapidly than some developers anticipated needing it.
Maven is hardly alone in chasing this. PayOS came out of stealth last April with partnerships tied to both card networks' programs. Ant International launched its Antom solution targeting APAC markets. Vox AI partnered with Adyen to enable drive-thru voice ordering with payment processing right at the speaker terminal—no app required.
Still, Maven's angle differs. The company isn't building a complete voice AI platform or targeting legacy enterprise call centers. It's positioning itself as developer infrastructure, the connective tissue between conversational AI platforms and payment processors.
How the Plumbing Actually Works
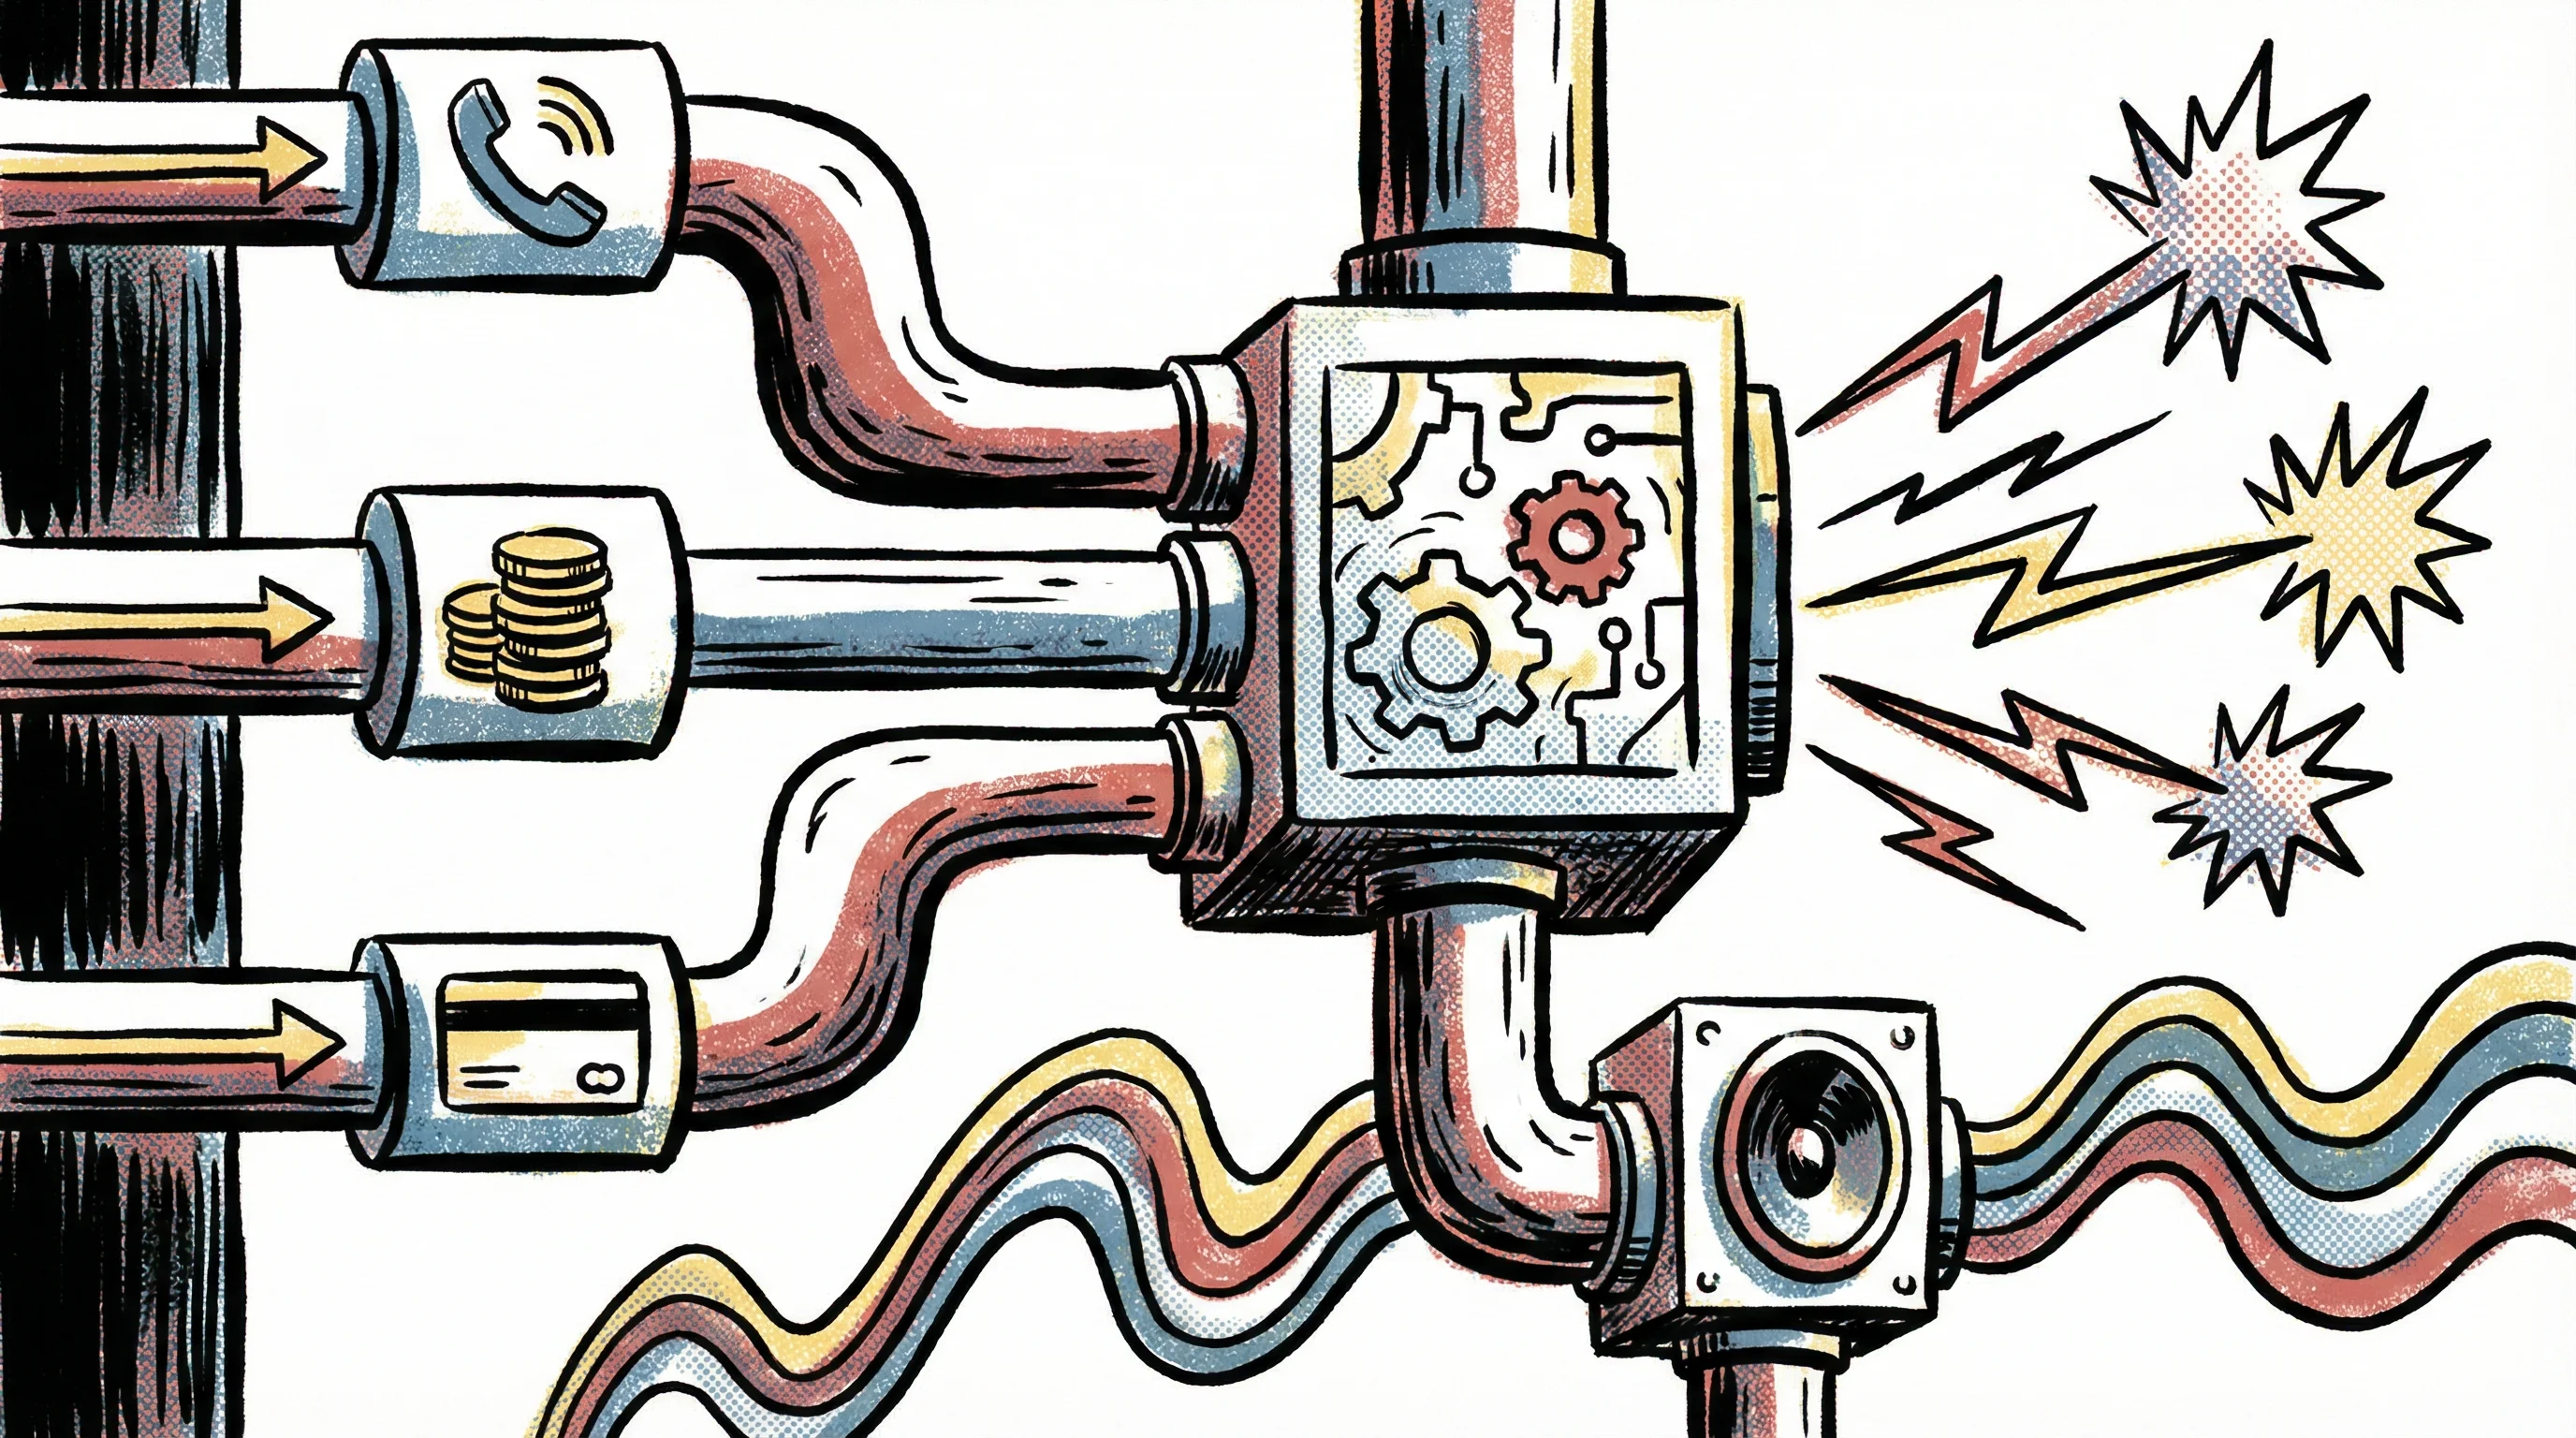
The company's public materials show a straightforward API. Pass in the caller's phone number, the amount in cents, your preferred payment gateway, and whether you're charging immediately or saving the card. Webhooks fire back with transaction status. Maven integrates with popular voice platforms—VAPI, Retell, LiveKit, Twilio—and supports processor relationships developers likely already have: Stripe, Braintree, Adyen, Authorize.net, Checkout.com, Worldpay, Square.
That last detail matters. Forcing developers to switch payment processors is a non-starter for most established operations. Maven sidesteps the issue by letting companies maintain existing gateway relationships.
The core selling point is PCI scope reduction. By keeping card data off customer servers entirely, Maven lets developers avoid the compliance maze that comes with handling sensitive payment information directly. It's not a revolutionary concept—Twilio's Pay product offers similar DTMF masking, and legacy vendors like Sycurio and PCI Pal have provided agent-assisted payment capture for years—but those solutions were designed for traditional contact centers, not modern AI agent stacks.
Maven appears to be repackaging these capabilities with session APIs and call transfer semantics that fit how conversational AI platforms actually work today.
What We Don't Know
The company's website doesn't specify Maven's own PCI compliance level, though it emphasizes the keep-data-off-your-servers value proposition. It's also unclear whether all listed payment gateways are generally available or if some remain aspirational roadmap items. Details about the SMS checkout provider and hosted payment page vendor aren't public yet.
Maven lists two employees on the Y Combinator directory and operates under the legal entity Lambda Systems, Inc. (also referred to as Maven Labs). The privacy policy shows a December 31, 2025 update. The company is offering demos and early access through trymaven.com, categorizing itself under Conversational AI, SaaS, Developer Tools, and Fintech—a taxonomy that suggests they're targeting AI agent builders, not general-purpose payment infrastructure buyers.
The Return-to-Agent Question
For developers building voice AI that actually transacts, the return-to-agent flow might be the most compelling detail. The ability to collect payment and seamlessly resume the conversation—without forcing the user to hang up, click a link, or start over—could prove meaningful as voice agents graduate from answering simple questions to facilitating actual commerce.
Whether Maven's abstraction layer becomes sticky infrastructure or a temporary gap-filler depends on execution and integration quality. It also depends on how quickly the major voice platforms build native payment capabilities themselves. Twilio could extend Pay. Retell or VAPI might partner with a processor directly. The window for third-party infrastructure plays can close faster than founders expect, particularly when larger platforms see revenue they'd prefer to capture internally.
But for now, at least, there's a gap. Voice agents are getting smarter, and businesses are deploying them in scenarios where payment collection isn't optional. Maven is betting that enough developers will pay for a cleaner solution to that problem—one that doesn't involve rebuilding payment infrastructure from scratch or watching conversion rates crater when the bot says "I'll text you a link."
It's infrastructure. It's unglamorous. And if voice commerce takes off the way the card networks seem to believe it will, it might just work.


