

The parade began, as it always does, with too many companies and too little time. On March 24, when Y Combinator unveiled its Winter 2026 batch—nearly 190 startups in total—investors watching the virtual presentations faced a now-familiar challenge: another Demo Day dominated by artificial intelligence pitches, another afternoon of sorting signal from ambitious noise.
But something clarified in the days after. Multiple venture capitalists, speaking independently to TechCrunch, kept returning to the same eight names. Not the flashiest presentations, necessarily. Not always the most hyped. Just the companies that had managed, in thirteen weeks with $500,000 in seed capital, to show something undeniable—traction that made skeptics lean forward, or technical accomplishments audacious enough to override the usual seed-stage caution.
At least two of these standouts were already in conversations about valuations approaching $100 million, a striking premium over the roughly $30 million post-money figure that's become standard for the batch. The spread across sectors tells you where sophisticated early-stage money thinks AI creates genuine leverage right now: autonomous security testing, yes, but also cattle-herding drones. Multimodal training data marketplaces alongside alternate-history strategy games.
The Companies That Showed Revenue Velocity
Consider Hex Security's timeline. Eight weeks. That's how long it took the company's autonomous penetration testing agents to surpass $1 million in annualized revenue, according to TechCrunch's March 28 reporting. It's the kind of number that transforms a three-minute pitch from theoretical to undeniable—continuous security testing powered by AI, addressing a line item CISOs already have budget for.
Luel's trajectory looks different but arrives at a similar place. The founders—CEO William Namgyal and COO Inigo Lenderking, both Berkeley dropouts—built a marketplace for rights-cleared multimodal training data. Foundation model developers need this stuff, badly, and they need it clean. By Demo Day, Luel had reportedly crossed nearly $2 million in annual recurring revenue. Six weeks from launch to that milestone. The company didn't exist when the batch started.
These aren't projected revenues. They're signed contracts, paying customers, the kind of proof that shortens every subsequent fundraising conversation.
AI Leaving the Data Center
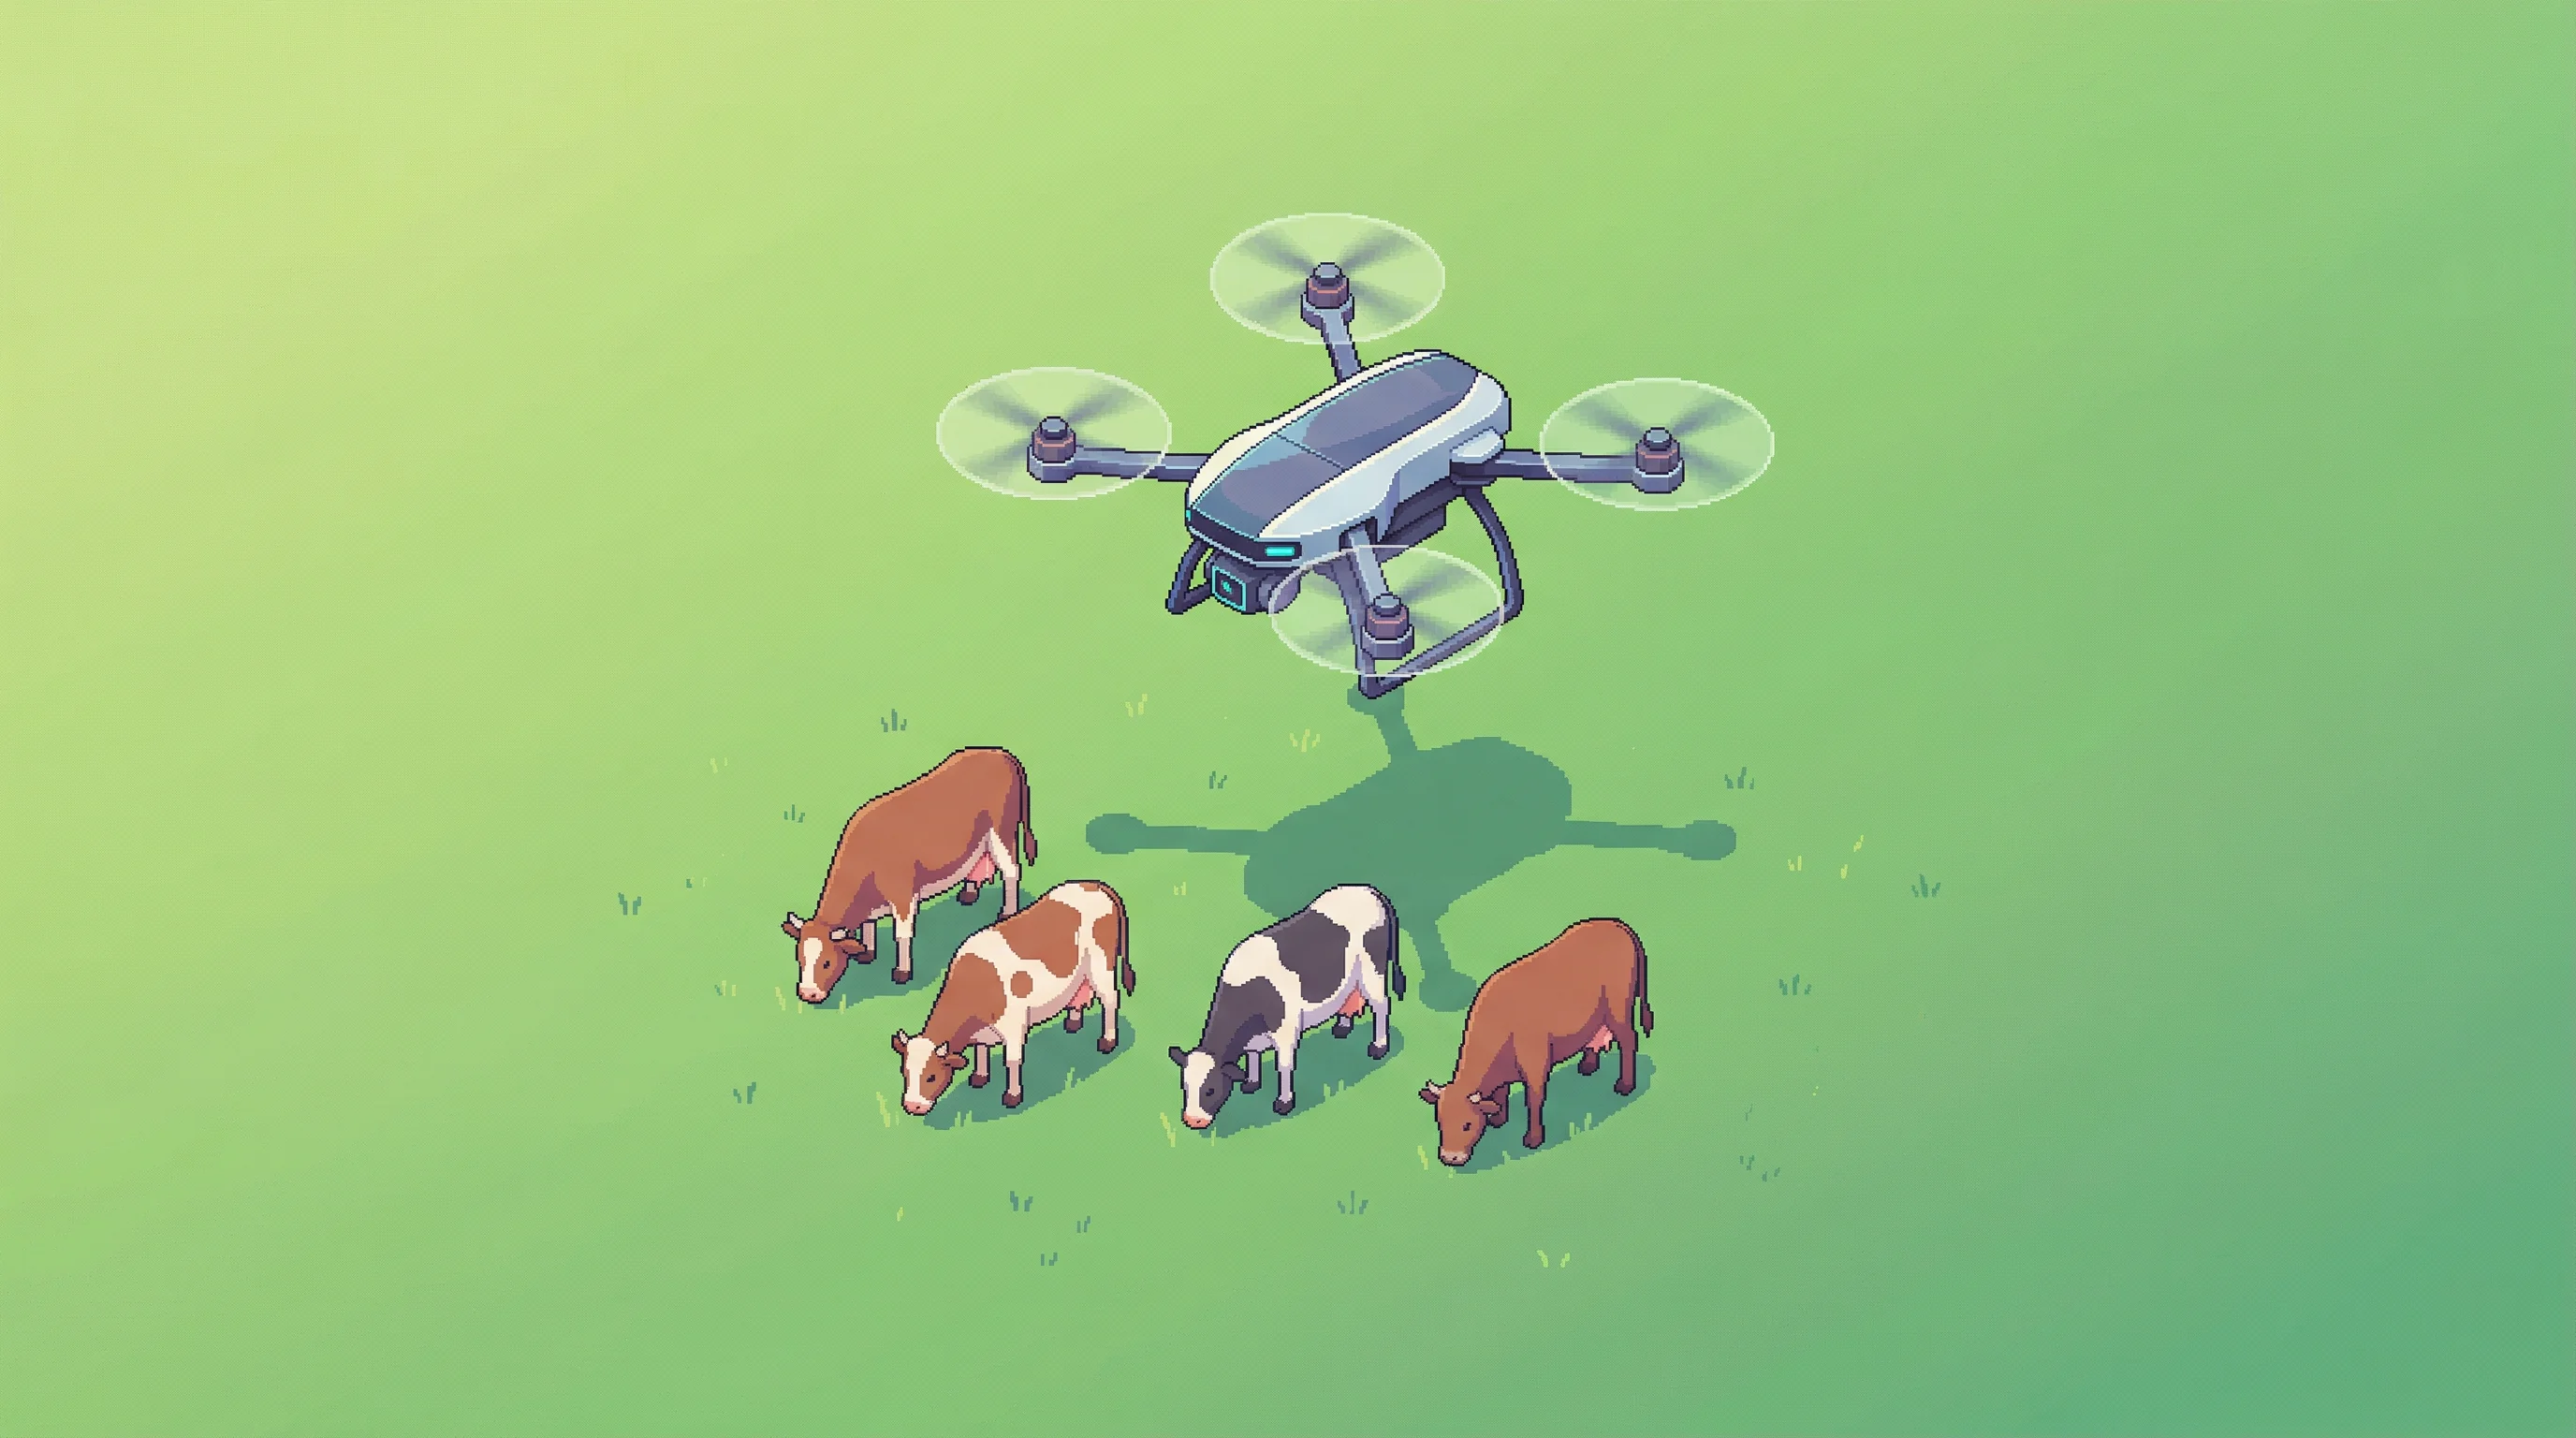
Then there's GrazeMate, which probably prompted more raised eyebrows per slide than anything else investors saw that afternoon. Autonomous drones that herd cattle. The pitch sounds almost comically niche until you dig into what the Berkeley-affiliated team is actually solving: real-time computer vision in unstructured outdoor environments, autonomous navigation across ranches measured in square miles, operational benefits that translate directly to rancher economics. The Launch YC post from February laid out the case in operational terms, not just technological ones.
Hard problems, as it turns out, can build moats—if you can prove the tech actually works.
Pax Historia took a different route entirely: consumer traction at speed. The alternate-history grand strategy platform had logged 35,000 daily active users and roughly 20 million gameplay rounds by Demo Day. In a batch overwhelmingly tilted toward B2B enterprise software, it's a consumer play banking on AI-generated narratives to create the kind of replayability that traditionally required armies of content creators and $50 million budgets.
Strategy games live or die on depth. Procedurally generated alternate histories, powered by large language models, offer depth without the ruinous development costs. Whether that thesis holds at scale remains to be seen, but the early engagement numbers caught attention.
Specialist Applications, Narrow Domains
Stilta and Pax Historia bookend a spectrum of specialized agents. Stilta targets IP and patent attorneys with agentic AI that's already deployed at firms like Roche—narrow domain expertise applied to high-value knowledge work where accuracy matters more than speed. TechCrunch noted the "Swedish founders halo effect" surrounding the team, though conversations with investors suggest paying enterprise customers mattered considerably more than pedigree.
The broader pattern here: AI enabling product categories that would have been economically impossible before. You couldn't build a strategy game with infinite narrative branches using human writers. You couldn't offer continuous, comprehensive patent analysis at accessible price points with associates billing by the hour. The technology shifts what's viable.
Infrastructure Bets That Barely Mention AI
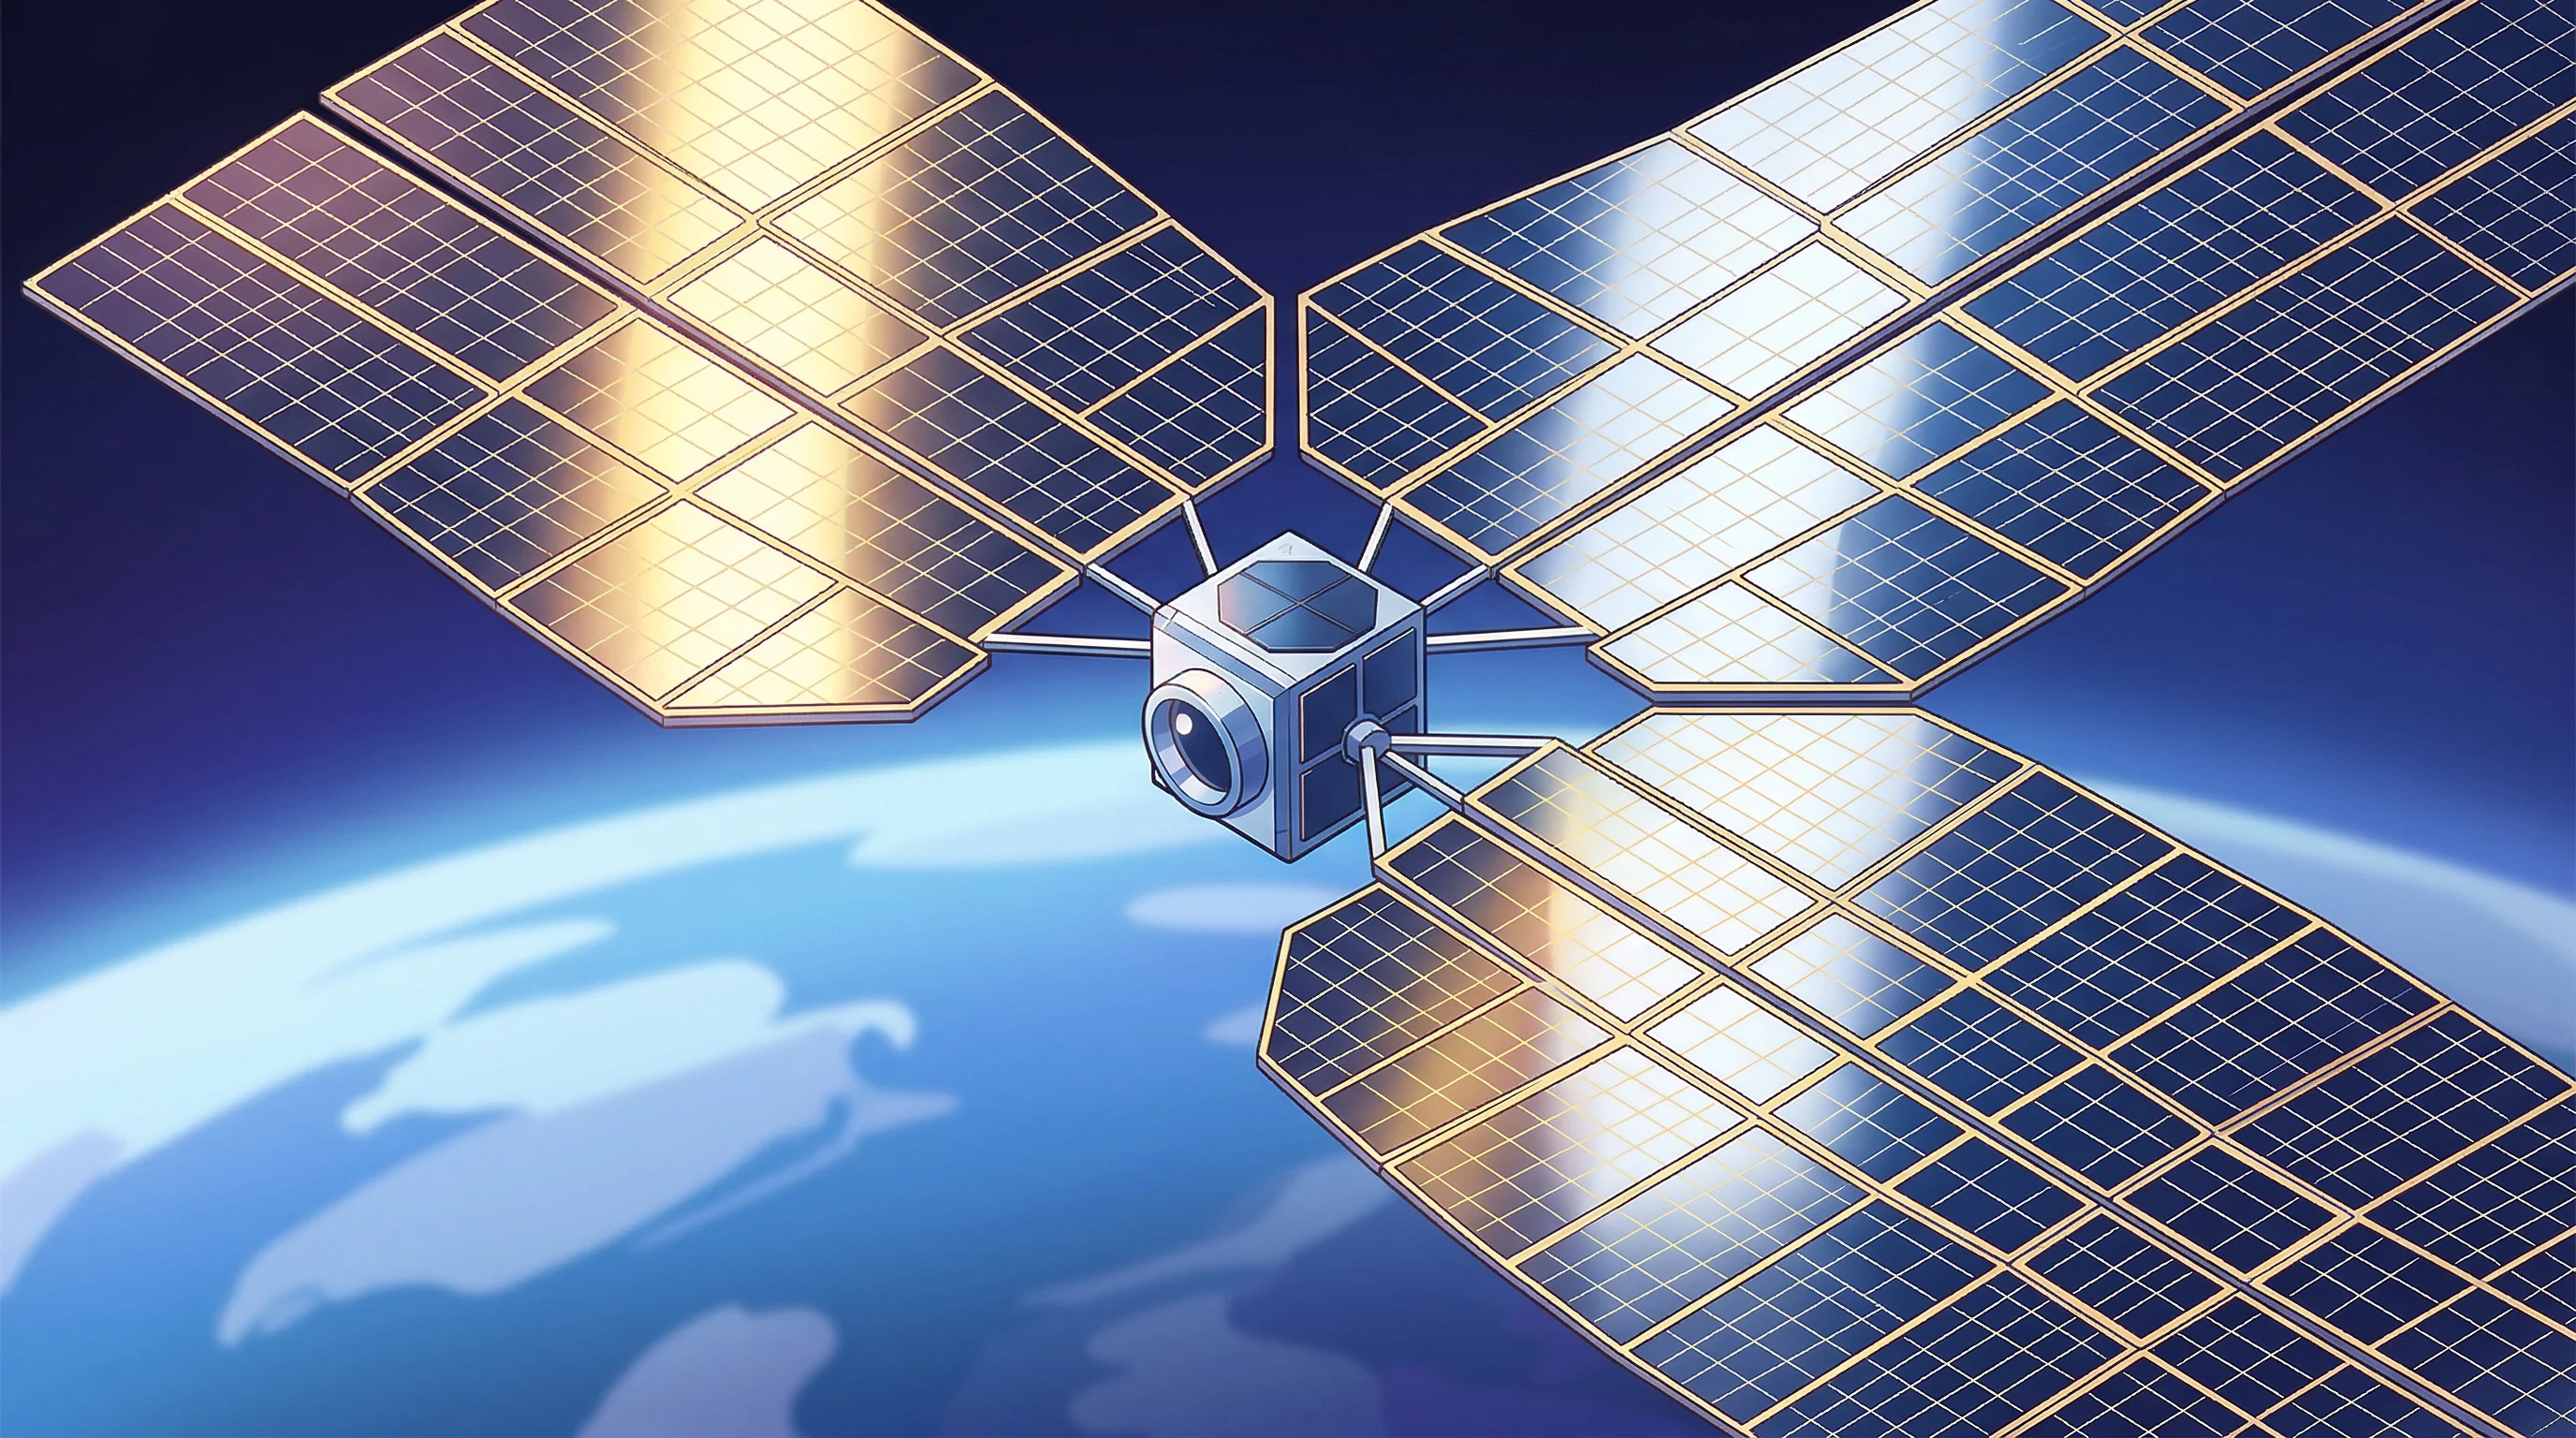
Not everything that made the investor favorites list screamed "machine learning startup." Beyond Reach Labs is building deployable solar arrays designed to launch compact and unfold to football-field dimensions in orbit. The company claims 10× power increases and 88 percent cost reductions compared to conventional space solar, pointing to $325 million in letters of intent and a first orbital flight planned for 2027.
Deep tech, certainly. AI? Not directly. Yet it made the list alongside the generative model plays.
Byteport's DART protocol attacks TCP with claims of 10× average speed improvements—up to 1,500× gains on reliable links, according to the pitch. Pure networking infrastructure. No large language models involved. GRU Space wants to build a lunar hotel by 2032, starting with "moon factory" production of bricks from regolith. The company cited $500 million in letters of intent, though the usual caveats apply to non-binding expressions of interest.
The inclusion of these deep infrastructure bets suggests investors are calibrating for different risk-return profiles even within a nominally AI-focused batch. Revenue traction offers one kind of signal. Technical feasibility that wasn't possible two years ago offers another. Sometimes you're betting on the founders' ability to execute on an audacious vision that happens to exist adjacent to, rather than within, the AI wave.
What Half a Million Dollars Buys You
Y Combinator's standard deal hasn't changed: $500,000 into each company, structured as $125,000 for 7 percent equity plus $375,000 on an uncapped SAFE with most-favored-nation terms. Identical across the batch. What varies wildly is what founders accomplish with thirteen weeks and that capital.
For these eight companies, it meant building enough proof—revenue, users, technical demonstrations—to justify valuations five to ten times higher than typical seed rounds in the current market. Several founders in the batch reportedly hit seven figures in ARR by Demo Day, though those claims remain unaudited and subject to the usual startup accounting flexibility.
The Demo Day format itself has evolved to reward companies that communicate traction in data points rather than promises. Roughly 1,500 investors and media received access to an invite-only site where YC posted individual pitch videos about twenty minutes after each live presentation. The compressed timeline and sheer volume mean differentiation increasingly comes down to vertical focus, distribution strategy, and early evidence of product-market fit.
The Batch in Broader Context
AI's continued dominance—unofficial tallies suggest roughly 90 percent of the batch has some AI component—means simply claiming to use machine learning no longer distinguishes you. The eight companies that captured sustained attention each found different angles. Some showed revenue hockey sticks that validated their go-to-market motion. Others demonstrated technical capabilities that sound like science fiction but happen to have paying customers or signed contracts backing them.
The valuations, the traction metrics, the letters of intent—all carry the standard disclaimers. Markets shift, products pivot, early revenue ramps don't always maintain their slope. Not every company with 35,000 daily users today will have 350,000 next year. Letters of intent, particularly in deep tech and space applications, can evaporate when it's time to wire money.
But for one March afternoon, and in the days of due diligence and term sheet negotiations that followed, these eight companies convinced some of the most experienced early-stage investors in Silicon Valley that they'd found something genuinely worth chasing. Whether that conviction proves prescient or premature won't be clear for years.
What's clear now is that even in a batch saturated with AI pitches, it's still possible to stand out—if you can show the work.


