

The moment Deutsche Bank switched on Wero for its 19 million German customers last summer, something shifted in European payments. Not loudly. Not with fanfare. But enough that people who watch this space started paying attention.
For the first time in years, a credible alternative to the Visa-Mastercard duopoly was actually live—not vaporware, not a pilot study gathering dust in Brussels. Real customers. Real transactions. Instant bank-to-bank payments with a tap of a phone.
By the end of 2024, more than 40 million users across Germany, France, and Belgium had access to the wallet. This year, e-commerce checkout begins rolling out across those markets. In-store tap-to-pay? That's slated for 2026, assuming the tech cooperates and merchants bite. And in February, the European Payments Initiative—the 16-bank consortium backing Wero—signed an interoperability deal linking its network to rival payment schemes in Italy, Spain, Portugal, and the Nordics.
The combined footprint, once everything connects, could reach 130 million users across 13 countries.
Which raises the question: Is this Europe's long-awaited answer to American card networks, or just another well-intentioned infrastructure project that merchants will quietly ignore?
What Wero Actually Does (And What It Doesn't)
Strip away the policy rhetoric, and Wero is straightforward: a digital wallet that moves euros directly between bank accounts in under 10 seconds. No card networks involved. No interchange fees bleeding into merchant costs. The underlying plumbing is SEPA Instant Credit Transfer, which has been around since 2017 but never had a consumer-friendly front end—until now.
Users can send money to friends or family using just a phone number or email address. Peer-to-peer was the opening act. E-commerce acceptance is the main event.
Germany saw its first live Wero checkouts last summer through processors like Worldline and PAYONE. Belgium followed in October 2025. France is queued up for early this year. The in-store piece—tap-to-pay at physical retailers—is penciled in for 2026, thanks in part to the EU's antitrust settlement with Apple that cracked open iOS NFC access to third-party wallets in July 2024.
The system includes Verification of Payee, which matches names to IBANs before money moves—a fraud deterrent baked into the EU's new Instant Payments Regulation. Daily sanctions screening, too. And unlike older account-to-account payment methods, Wero promises buyer protection and dispute resolution for e-commerce, addressing one of the reasons people trust cards in the first place.
But let's be clear: Wero isn't replacing Visa and Mastercard, despite what went viral on social media earlier this year. European officials have said as much, repeatedly. This is about competition and choice, not elimination. The card networks aren't going anywhere. They're just getting company.
The 16-Bank Coalition (And Why It Might Actually Work This Time)
Wero is the brainchild of the European Payments Initiative, a consortium that reads like a who's-who of continental banking: BNP Paribas, Deutsche Bank, ING, KBC, ABN Amro. The German savings bank and cooperative networks—DSGV and DZ BANK—are in. So are payment processors Worldline and Nexi.
Unlike past attempts at a pan-European payment system (remember Monnet?), this one has scale baked in from the start. The group acquired iDEAL—the dominant Dutch online payment method—in October 2023, along with Belgium's Payconiq International. Both are being folded into Wero. ING expects the full iDEAL migration to wrap by the end of 2027. In France, Wero is effectively the successor to Paylib. In Belgium, it's absorbing Payconiq's user base.
Neobank N26 joined in December 2025—a telling signal that fintech upstarts see an opportunity here. Five more Belgian banks (Argenta, Bank Van Breda, Beobank, Crelan, vdk) are scheduled to onboard in the first half of this year. Luxembourg's major institutions—Spuerkeess, BGL BNP Paribas, BIL, POST, Raiffeisen—are targeting a consumer launch by mid-2026.
The 48.5 million user figure cited in company materials as of February reflects the reach of participating banks, not necessarily active wallet users. It's potential, not performance. But the footprint is real, and it's growing faster than most outsiders expected.
Merchant Acceptance: Where Theory Meets Reality
This is where things get messy.
Worldline started enabling Wero checkouts in Germany last summer. Belgium went live in October. France is next. PAYONE, a Worldline joint venture, announced nationwide e-commerce acceptance in Germany last November. Nexi partnered with payment gateway Computop to act as a Wero acquirer starting in Q3 2025, with in-store rollout planned for this year.
Payment service providers like PPRO, Nuvei, and Airwallex have also signed on to integrate Wero for their merchant clients. Early pilots included a proof-of-concept transaction through the online shop of FC Kaiserslautern, a German football club, in late 2024. (Yes, buying a jersey with your banking app counts as a milestone now.)
Pricing remains a work in progress. The Instant Payments Regulation mandates that banks can't charge consumers more for instant transfers than standard ones—meaning Wero is essentially free for peer-to-peer use at most institutions. Merchant fees vary by acquirer and country. Industry sources have pointed to rates around 0.77 percent in Germany, potentially below typical card interchange in some categories, though gateway fees can add to the total. The economics are still being tested in live environments, and it's anyone's guess where they settle.
Here's the challenge: merchants don't change payment infrastructure lightly. Integration costs money. Training staff takes time. And unless Wero drives demonstrably lower costs or higher conversion rates, many retailers will stick with what works.
Cards work.
The Regulatory Rocket Fuel
Wero's rollout coincides with the most aggressive regulatory push for instant payments Europe has ever attempted.
The EU's Instant Payments Regulation, adopted in February 2024, requires payment service providers in the euro area to receive instant euro payments as of January 9, 2025. Sending them—complete with Verification of Payee—became mandatory by October 9, 2025. Non-euro area providers have deadlines stretching into 2027.
The regulation also enforces price parity: instant payments can't cost more than standard transfers. Fraud controls are embedded. Verification of Payee. Daily sanctions screening. The whole compliance suite.
The European Central Bank's TARGET Instant Payment Settlement (TIPS) system processed about 1.35 billion instant payments in 2024, with 99.99 percent executed within five seconds. EBA Clearing's RT1 and STEP2 systems have been upgraded to meet the new mandates, including a pan-European VOP solution that launched in 2025.
The infrastructure is there. The rules are live. What Wero does is put a consumer-facing interface on top of it all.
The Interoperability Gambit
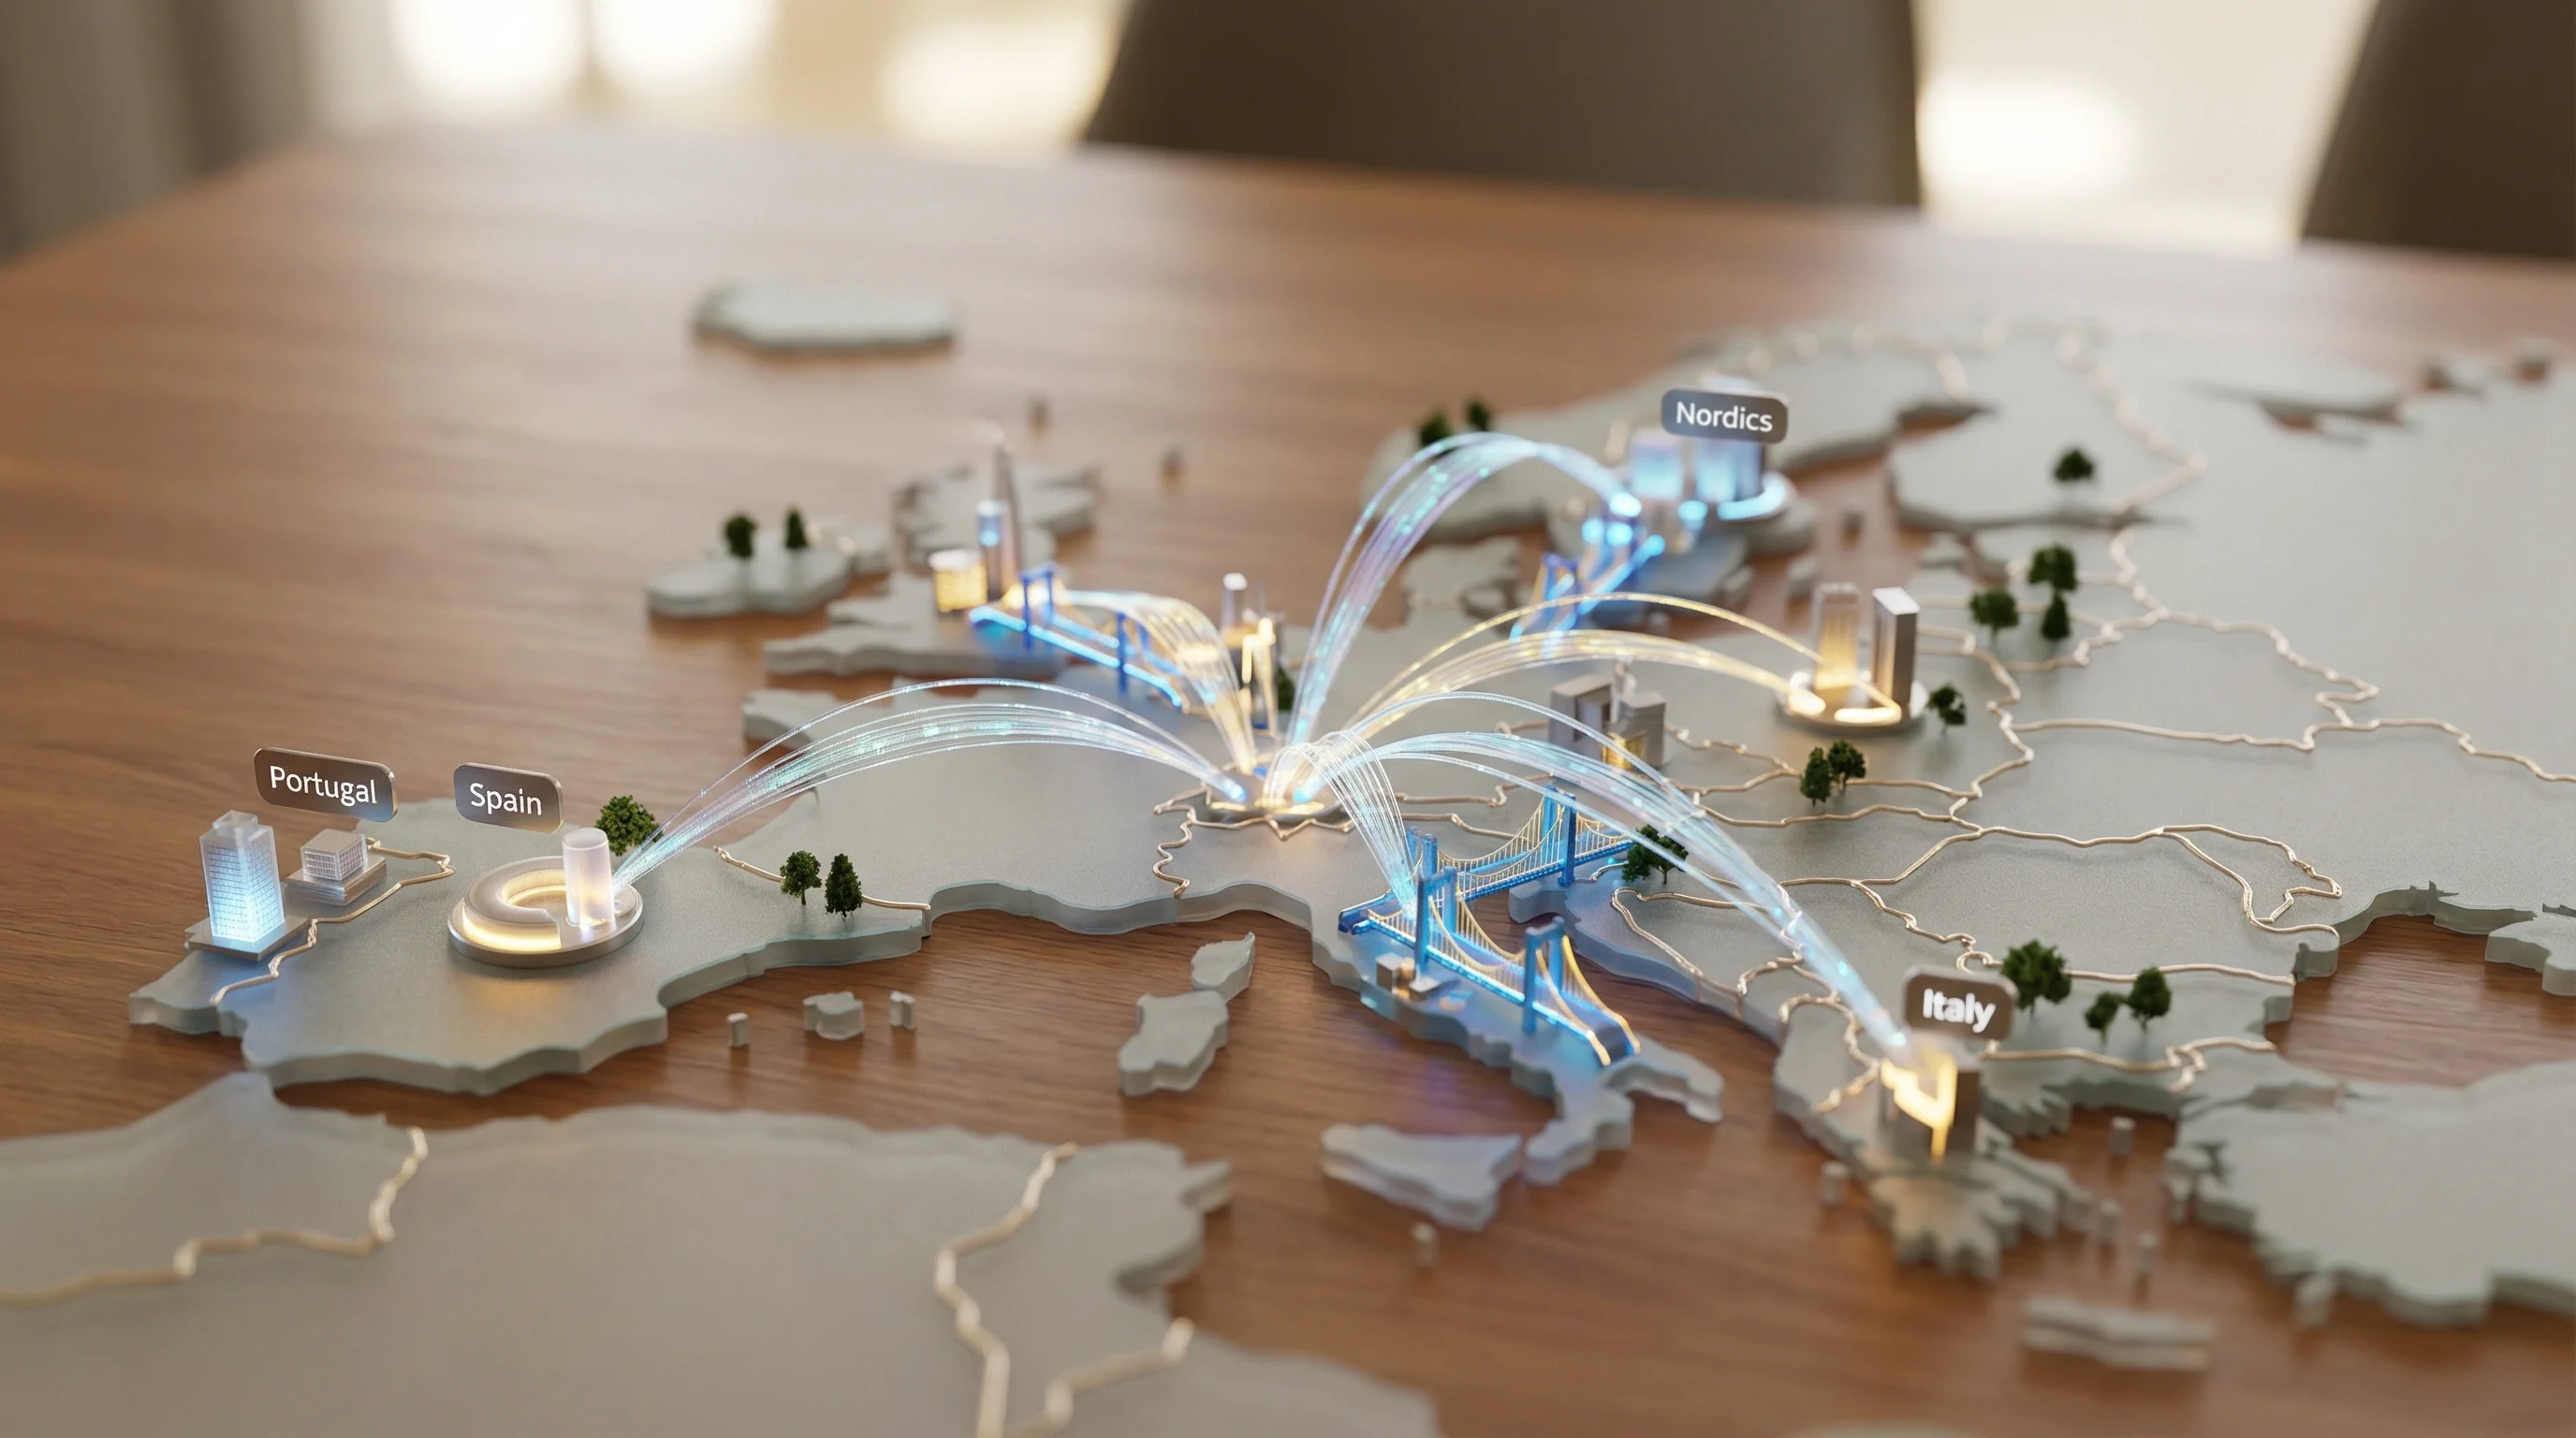
In February, the European Payments Initiative signed a memorandum of understanding with the EuroPA alliance—a rival coalition that includes Italy's Bancomat, Spain's Bizum, Portugal's MB WAY, and the Nordics' Vipps MobilePay.
The goal? Cross-border peer-to-peer payments between the two networks by the end of this year. E-commerce and point-of-sale interoperability by 2027.
EuroPA had already connected its founding members for P2P in March 2025, linking more than 50 million users across Italy, Portugal, Spain, and Andorra. Poland's Blik and the Netherlands' IRIS joined later. The plan calls for a central interoperability hub, with governance and technical details still being hammered out.
If it works—and that's a meaningful if—the combined reach could hit 130 million users across 13 markets.
That's network effect territory. Not quite Visa-scale, but enough to make merchants take notice.
What This Isn't (And Why That Matters)
The narrative that Europe is "banning" Visa and Mastercard with a $24 trillion replacement system? That's fiction.
The "$24 trillion" figure references the total value of retail payments processed in Europe annually—ECB data show euro-area retail payment systems handled about €26.4 trillion in just the second half of 2024. It's not a budget. It's not a single new system. It's the size of the market.
Visa and Mastercard still command roughly 61 percent of euro-area card transactions. Thirteen euro-area countries rely entirely on international card schemes for card acceptance. European policymakers, including ECB officials quoted in a February 2025 press release, frame the objective as reducing over-reliance and fostering "European alternatives" for strategic and competitive reasons—not outlawing US-based networks.
In fact, Visa is leveraging the same Digital Markets Act changes that opened iOS NFC access, partnering with local wallets like BBVA Pay, Klarna, and Vipps MobilePay to offer tap-to-pay across Europe. The landscape is getting more competitive, not consolidating around a single winner.
This is a three-way race. Maybe four-way, if you count Apple Pay.
The Open Question
The European Payments Initiative's CEO told the Financial Times in February that European alternatives to Visa and Mastercard are "urgently" needed. The framing is explicit: this is a sovereignty play as much as a commercial one. Europe wants payments infrastructure it controls—governance inside the continent, data residency inside the continent.
Fair enough. But wanting something and getting it are different things.
The technical rails are live. The regulatory framework is in place. The interoperability roadmap is published. Banks have committed capital. Merchants are starting to integrate.
What's missing is proof that consumers and retailers will actually shift behavior.
Moving users from cards—with their embedded rewards, fraud liability protections, and decades of merchant acceptance—to a new wallet requires more than policy mandates and better economics. It requires trust. Convenience. Volume. Enough transaction flow to justify the integration headaches and the customer service training and the checkout button real estate.
The next 18 months will tell the story. Either Wero becomes the payment method that finally gives Visa and Mastercard a real challenger in Europe, or it joins the long list of bank-backed initiatives that looked great on paper but never quite caught fire.
The pieces are on the board.
Now comes the hard part.


