

Vincent Chen logs into a carrier portal. Or rather, his AI agent does. Then another portal. And another. By the time a human broker would still be hunting for the right PDF form, Chen's system has already submitted applications to a dozen underwriters, drafted follow-up emails, and started negotiating terms for a high-risk client most brokers wouldn't touch with a ten-foot pole.
This is Panta Insurance Services—a four-person team, a rack of Mac Minis in San Francisco, and a bet that the labyrinthine back office of commercial insurance can finally be automated. The company emerged from Y Combinator's winter cohort with a provocative pitch: autonomous agents that deliver bindable quotes ten times faster than traditional brokers. Not software to assist brokers. The agents are the brokers.
Whether that's audacious or merely inevitable depends on whom you ask. But Chen and his cofounder Frank Wang didn't just build the technology and hope it would work. They became licensed insurance brokers themselves, manually placed hundreds of accounts, then systematically automated every step they'd learned. It's a grind-it-out approach that tech founders often talk about but rarely execute.
The Unglamorous Heart of Insurance
Commercial insurance brokerage is not typically associated with Silicon Valley disruption. It's a world of ACORD forms, surplus lines regulations, and underwriters who still prefer phone calls to Slack messages. For hard-to-place risks—think explosive laboratories, armed security contractors, or hazmat trucking operations—the process can stretch across weeks of back-and-forth negotiations, declined submissions, and manual paperwork that would make a DMV clerk weep.
Panta operates as a full-stack brokerage, not a software vendor. The distinction matters. The company holds a California Surplus Lines Broker license and claims coverage across all 50 states, though that multi-state licensing footprint hasn't been independently verified in public filings. The AI agents handle what brokers typically spend 80 percent of their time doing: portal logins, form filling, underwriter correspondence, certificate issuance, endorsement management. The tedious scaffolding of the business.
The firm focuses on Excess & Surplus lines, the segment that handles risks standard carriers avoid. According to industry data, E&S premium volume hit $90.3 billion across stamping-office states in 2025, up from $81 billion the prior year. Panta's launch materials cite the market at $125 billion—a self-reported figure that may reflect broader definitional boundaries or different market segments than the stamping-office data captures.
One case study from the company's launch illustrates the speed gap: an armed security outfit seeking coverage for a 100,000-person stadium received bindable quotes in three days after six other brokers passed. The placement required roughly 60 emails. A human team would likely have needed weeks. Panta's agents handled it in what amounts to a long weekend.
Mac Minis and the Philosophy of "Just Use What Exists"
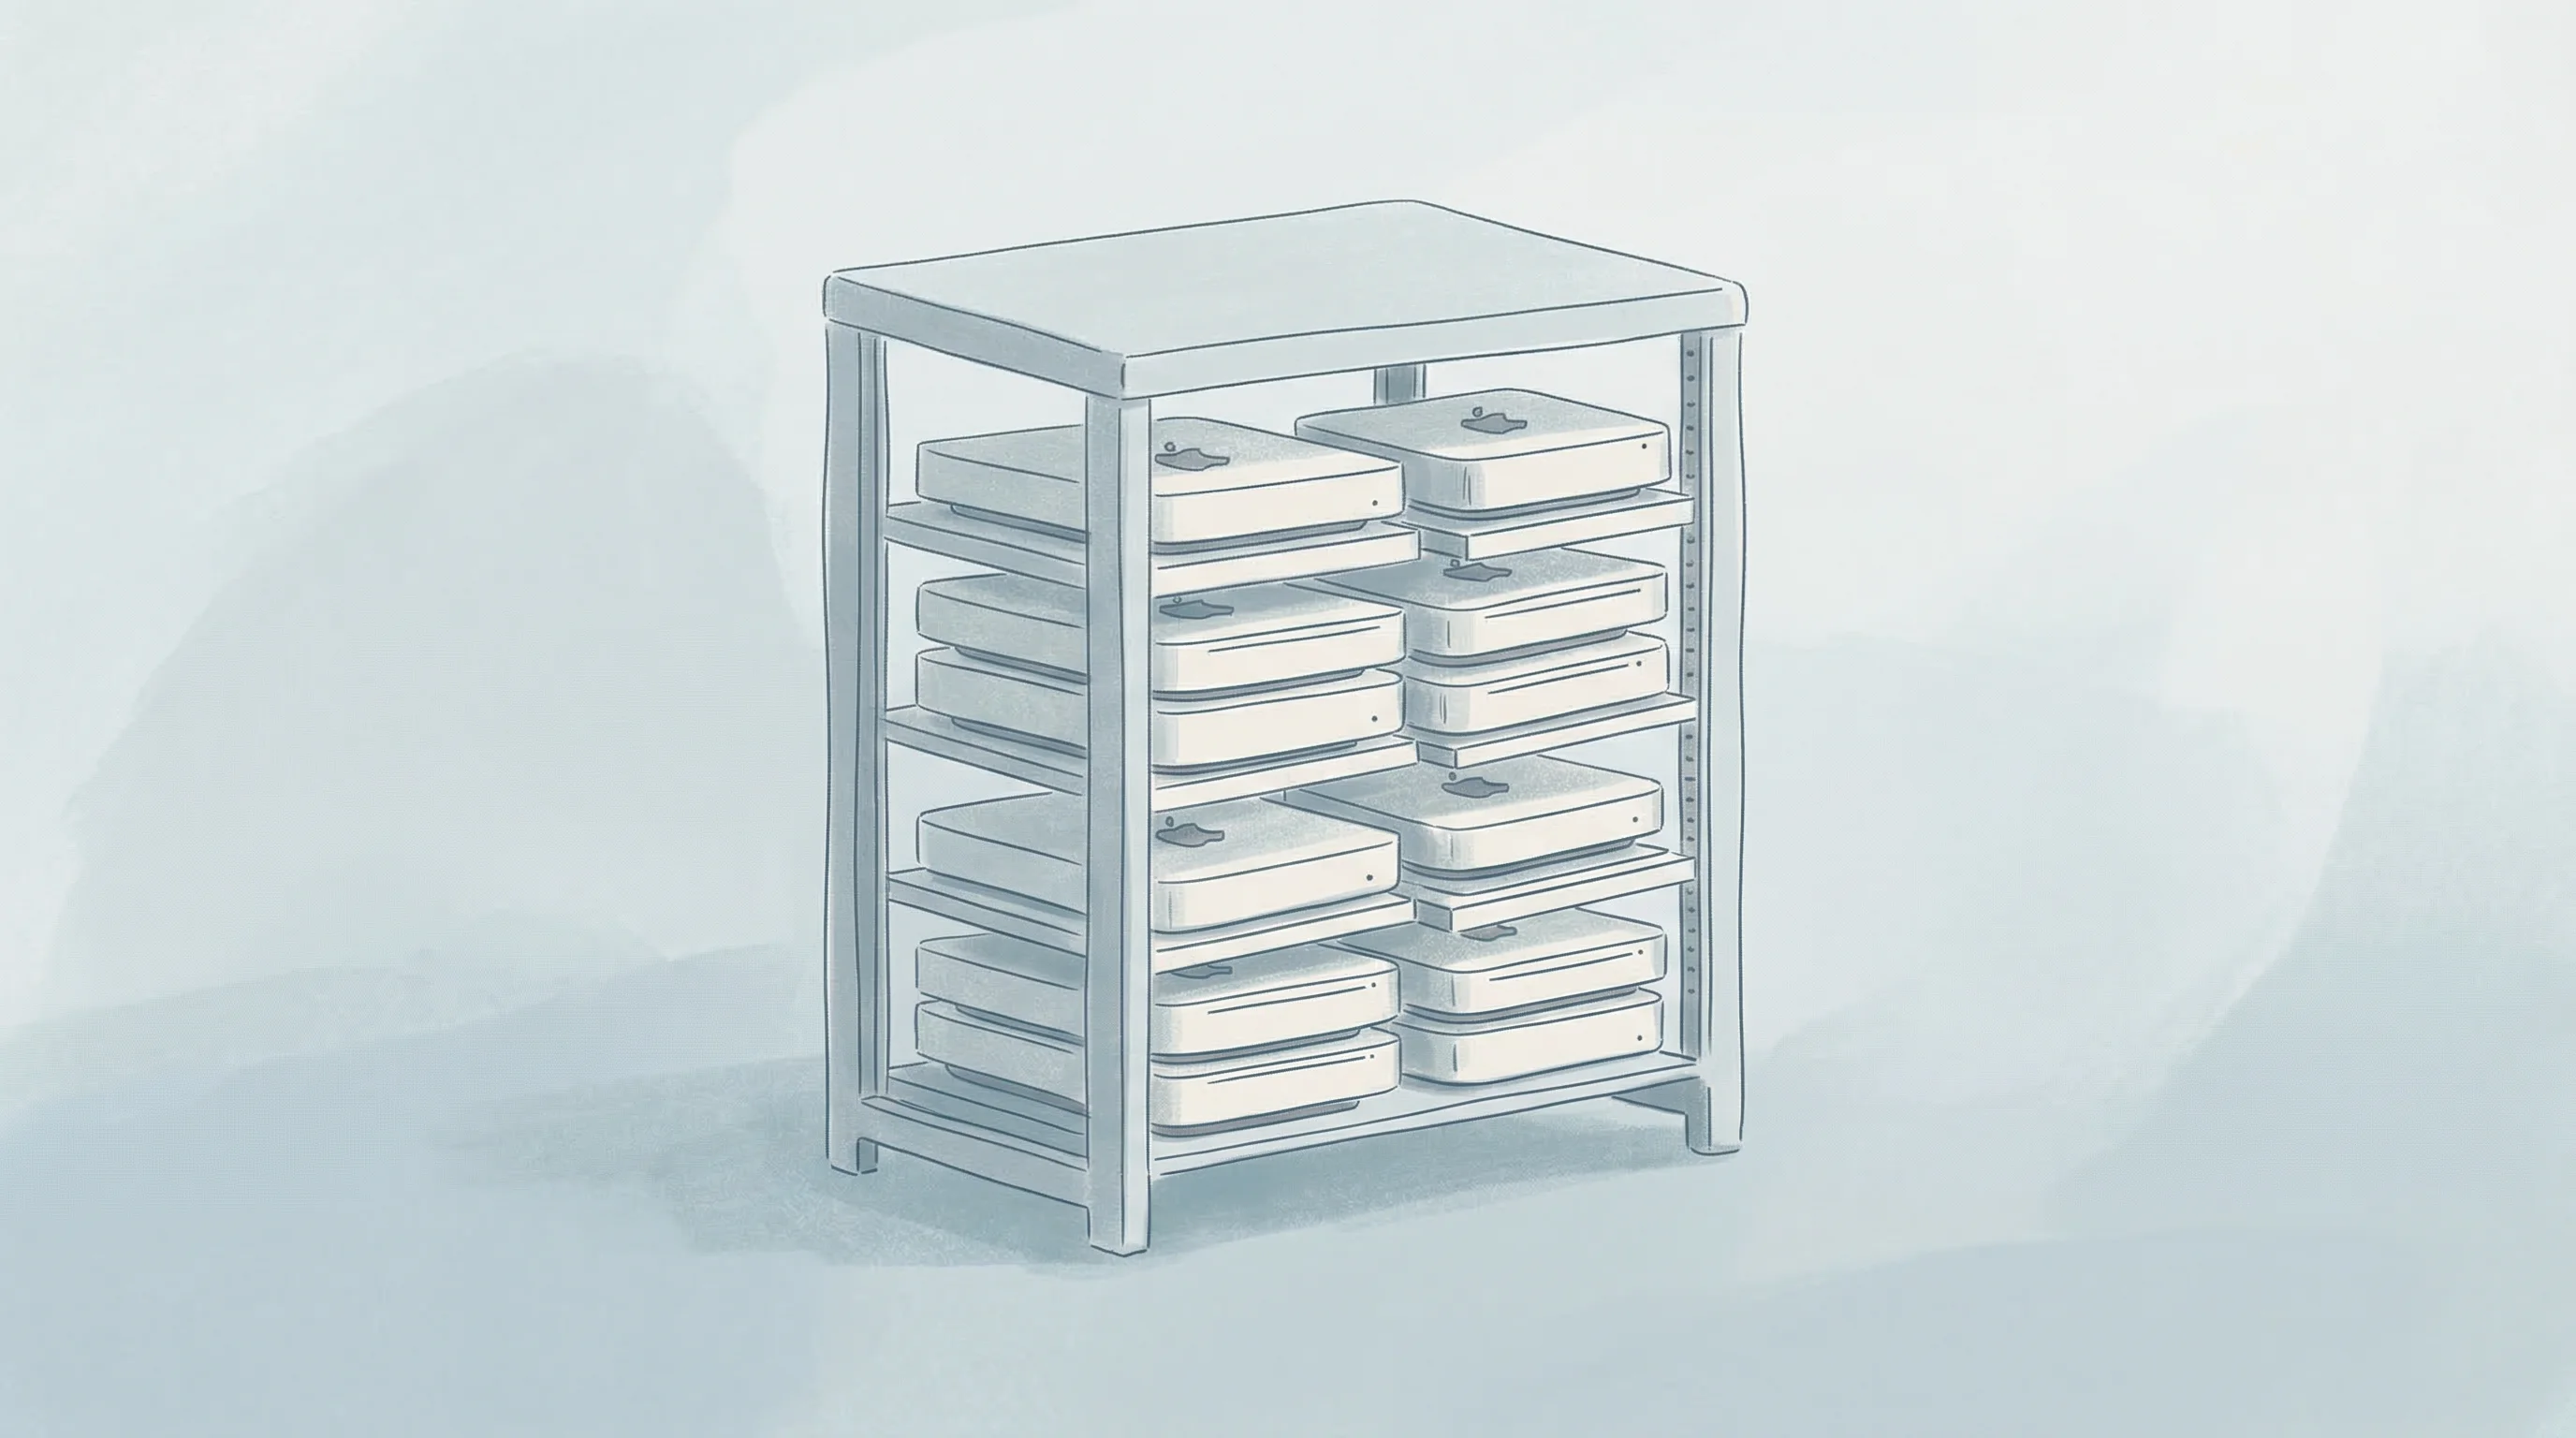
The technical architecture is almost charmingly low-tech in its hardware choices. A rack of Mac Minis—nothing exotic, nothing cloud-native in the buzzy sense. On those machines, Panta runs what it calls "OpenClaw-style AI operators," agents that navigate the same creaking infrastructure human brokers do: web portals built in 2008, email threads that spiral into chaos, PDFs that don't parse cleanly, phone calls to underwriters who may or may not answer.
No APIs. No carrier partnerships for privileged data access. No integrations that require six months of enterprise sales cycles. The agents simply operate inside the existing plumbing of the commercial insurance market, the way a human would—just faster, and without needing lunch breaks.
According to the company, the system includes human approval gates for high-stakes actions and maintains full audit logs. The agents went into production in December 2025, the founders report. In LinkedIn posts from early this year, the team claimed to have automated an "explosive oil and gas laboratory insurance" placement in minutes and demonstrated a "20x" improvement in submission workflows during internal Y Combinator demos. Those are bold claims. They're also the kind of claims that demand scrutiny, which so far has been hard to apply given the company's limited public disclosure.
The Pivot That Mattered
Before launch, Chen and Wang made a call that likely defines the company's trajectory. "We stopped selling software and became the broker," Chen wrote in Panta's Y Combinator launch post. The software-as-a-service model for insurance brokers is crowded—Aon's Broker Copilot, Zywave's agentic AI tools, Applied Systems' suite, and others. Selling into that market means navigating enterprise sales, legacy integrations, and the inertia of incumbent workflows.
Panta went the other direction. Build the entire business model around autonomous operation, cut out the humans where possible, and compete on speed and economics. It's the Flexport model, not the Shopify model—own the operations, not just the software layer.
Both founders obtained their own commercial broker licenses. Wang, who built Rust infrastructure and real-time messaging systems at Apple, brought the low-level engineering chops. Chen, who led work on Google's Vertex AI and NotebookLM, understood how to wrangle foundation models into production systems. Together, they worked placements manually before writing a line of code to automate them—an approach that mirrors what Y Combinator calls "founder mode," though perhaps more literally than most.
The company claims access to over 100 A-rated carriers and a 99 percent placement rate. Both figures are self-reported and lack third-party verification. The website lists coverage across General Liability, Commercial Auto, Property, Workers' Comp, Excess/Umbrella, Cyber, D&O, and other lines, serving niche segments like cannabis operations, bars, gyms, medical spas, food trucks. Exactly the kinds of businesses that give standard carriers heartburn.
The Market Is Moving, Just Not in One Direction
The E&S segment is undeniably growing. Mid-2025 data showed surplus lines premium at $46.2 billion, up 13.2 percent year-over-year. The market absorbs risks that admitted carriers won't underwrite, which means specialized expertise and higher commissions. It also means speed can be a genuine competitive advantage. Businesses with unusual risk profiles often need coverage immediately—construction projects that can't start without proof of insurance, events that require liability coverage by a certain date.
But Panta isn't the only startup reading this opportunity. Harper, also from Y Combinator's winter batch, launched a similar AI-native brokerage model months earlier. Established players like Pathpoint offer digital E&S placement platforms. Bold Penguin expanded its specialty and E&S access through an acquisition of SquareRisk in October. Even the legacy broker tech stack is evolving—Patra claims its platform automates up to 85 percent of commercial policy volume, and Majesco released AI agent features last fall.
Goldman Sachs noted in a March report that broker-led distribution is likely to remain dominant in commercial property and casualty insurance. The channel, in other words, has staying power even as the workflows inside it get rebuilt. Whether that favors nimble startups or incumbent brokers with deeper carrier relationships and existing client books is an open question.
What We Know, and What We Don't
CB Insights lists Panta with $500,000 in funding on a convertible note, with Y Combinator as the investor—likely the standard deal rather than an external seed round. No formal fundraise has been announced. The company is scheduled to present at Y Combinator's Demo Day on March 24, where the founders will presumably pitch a larger round. Team social posts hint at ambitions to insure rockets and satellites in 2026, which would be a notable expansion from food trucks and gyms.
The company's marketing materials claim "hundreds of businesses" have switched to Panta. But there are no client logos, no named testimonials, no revenue figures. The traction remains, in a word, unverifiable. Panta has not disclosed automation coverage percentages, error rates, or margin profiles—standard metrics for evaluating AI-powered operations, particularly in a regulated industry where mistakes can trigger compliance issues or litigation.
What the company has demonstrated, at least in principle, is that the commercial insurance back office—long considered too tangled and regulated for full automation—can run on AI agents with the right infrastructure and licensing. The system exists. It's in production. The question now is whether it scales.
Perhaps it becomes a durable business that reshapes how small and mid-sized businesses buy commercial insurance. Perhaps it proves the concept just in time for larger competitors—Marsh McLennan, Aon, Gallagher—to replicate the model with vastly more carrier relationships and client trust. Or perhaps the economics of E&S brokerage don't actually improve enough to matter when you replace humans with agents that still require oversight, compliance infrastructure, and the occasional phone call to an underwriter who doesn't trust robots.
For now, the Mac Mini rack in San Francisco is handling placements that used to require teams of licensed brokers. And doing it faster, if the company's claims hold up under scrutiny. That alone is worth watching.


