

Somewhere in Silicon Valley, champagne corks are popping. They should be—global venture capital deployed $510 billion in the first half of 2026 alone, already eclipsing the entire previous year's total. But if you're clutching a pre-seed pitch deck, scanning your inbox for warm intros, you'd be forgiven for wondering where all that money actually went.
Because it almost certainly didn't come anywhere near you.
North American seed and angel funding collapsed to roughly $4.9 billion in the second quarter, down 27% year-over-year, according to Crunchbase data released in July. Here's what makes that figure particularly jarring: while two consecutive quarters each topped $200 billion in venture deployment, CB Insights reported that global deal count fell to its lowest level in more than a decade. Record capital deployed. Fewest deals cut. The arithmetic doesn't reconcile—unless you understand where the money is actually pooling.
Where the Gravity Well Is
The 2026 venture capital landscape looks less like a thriving ecosystem than a physics problem. Capital concentrates around a handful of AI giants and mega-funds with the pull of a black hole. By mid-year, KPMG's Venture Pulse pegged annual global VC investment at $560.4 billion, a five-year high driven almost entirely by late-stage AI mega-rounds that would have seemed fantastical just 24 months earlier.
The concentration shows up everywhere you look. In the first quarter, five venture firms captured 73.1% of new fund commitments in the United States, according to PitchBook and the National Venture Capital Association. AI startups, meanwhile, commanded roughly 80% of all global venture dollars during the same period. U.S. companies alone received approximately 88% of AI funding by mid-year, Crunchbase estimates suggest.
Five deals represented an outsized share of first-quarter deal value—OpenAI's jaw-dropping $122 billion round, Waymo's $16 billion raise, and similar outliers that reset the ceiling for what "mega-round" even means.
Then there's this: the median U.S. venture fund size dropped to $15.3 million in the first quarter, down from $25 million the prior year. Read that twice. While a few mega-funds—Andreessen Horowitz's $14.2 billion vehicle, Thrive's $10 billion fund, Founders Fund's $10.6 billion close—vacuum up limited partner commitments, smaller and emerging managers are finding it harder to raise meaningful capital. The market has bifurcated into something resembling a barbell: mega-funds writing nine-figure checks to established AI labs on one end, and a long tail of micro-VCs scraping together smaller vehicles for everything else on the other.
What used to be a middle has largely vanished.
The Three Forces Starving the Seed Stage
Three interrelated dynamics are starving the earliest stages while inflating the top of the funnel, and they're feeding on each other in ways that make the concentration self-reinforcing.
First, the AI infrastructure arms race. Hyperscalers are pouring unprecedented sums into data centers and compute capacity. S&P Global Ratings projected top U.S. cloud providers' 2026 capital expenditures north of $700 billion; TrendForce pegged the top nine cloud service providers' combined spending near $830 billion. When Microsoft reports a single quarter with capex up 70% to $41 billion, and Meta guides fiscal 2026 capex between $130 billion and $145 billion—figures disclosed in late July earnings calls—it becomes clear where the fuel is going. That infrastructure build demands venture backing for the AI labs training on it, creating a feedback loop that channels billions into a small cluster of late-stage companies while leaving the rest of the market scrambling.
Second, limited partner constraints are tightening. Exit velocity hasn't kept pace with deployment. S&P Global Market Intelligence found that total private equity and venture exits in the first half fell 6% year-over-year by deal count, even as IPO proceeds tripled on the strength of a handful of mega-offerings (according to mid-year reports from EY and PwC). LPs aren't seeing broad distributions, so they're concentrating re-ups with proven, large managers rather than taking flyers on new firms. Charles Hudson, managing partner at Precursor Ventures, noted in a July TechCrunch interview that raising a first institutional round has become markedly harder. The bar is higher, the timeline longer, and patience among capital allocators is thin.
Third, the composition of investors has shifted dramatically. The NVCA's 2026 Yearbook—covering 2025 data—showed nontraditional investors like corporates, sovereigns, and asset managers participating in roughly 30% of deals but accounting for 83% of investment value. These players write big checks at late stages; they're not staffed to sift through hundreds of seed pitches or spend weekends at pitch competitions. As AI rounds cycle faster and attract more nontraditional capital, fewer partner slots remain for small, early-stage bets that might take years to develop.
The policy backdrop adds another layer of friction. EU AI Act obligations for general-purpose AI providers began applying August 2, with compliance costs and timelines extending into 2027–2028 under the Digital AI Omnibus adopted in late July. In the U.S., revised export license policies on advanced AI chips—H200, MI325X—and a 25% tariff on certain computing hardware, effective mid-January via Section 232 authority, have complicated hardware access and capital deployment strategies. Regulatory complexity favors well-capitalized incumbents over bootstrapped startups scrambling to navigate compliance.
The Deals That Ate the Market
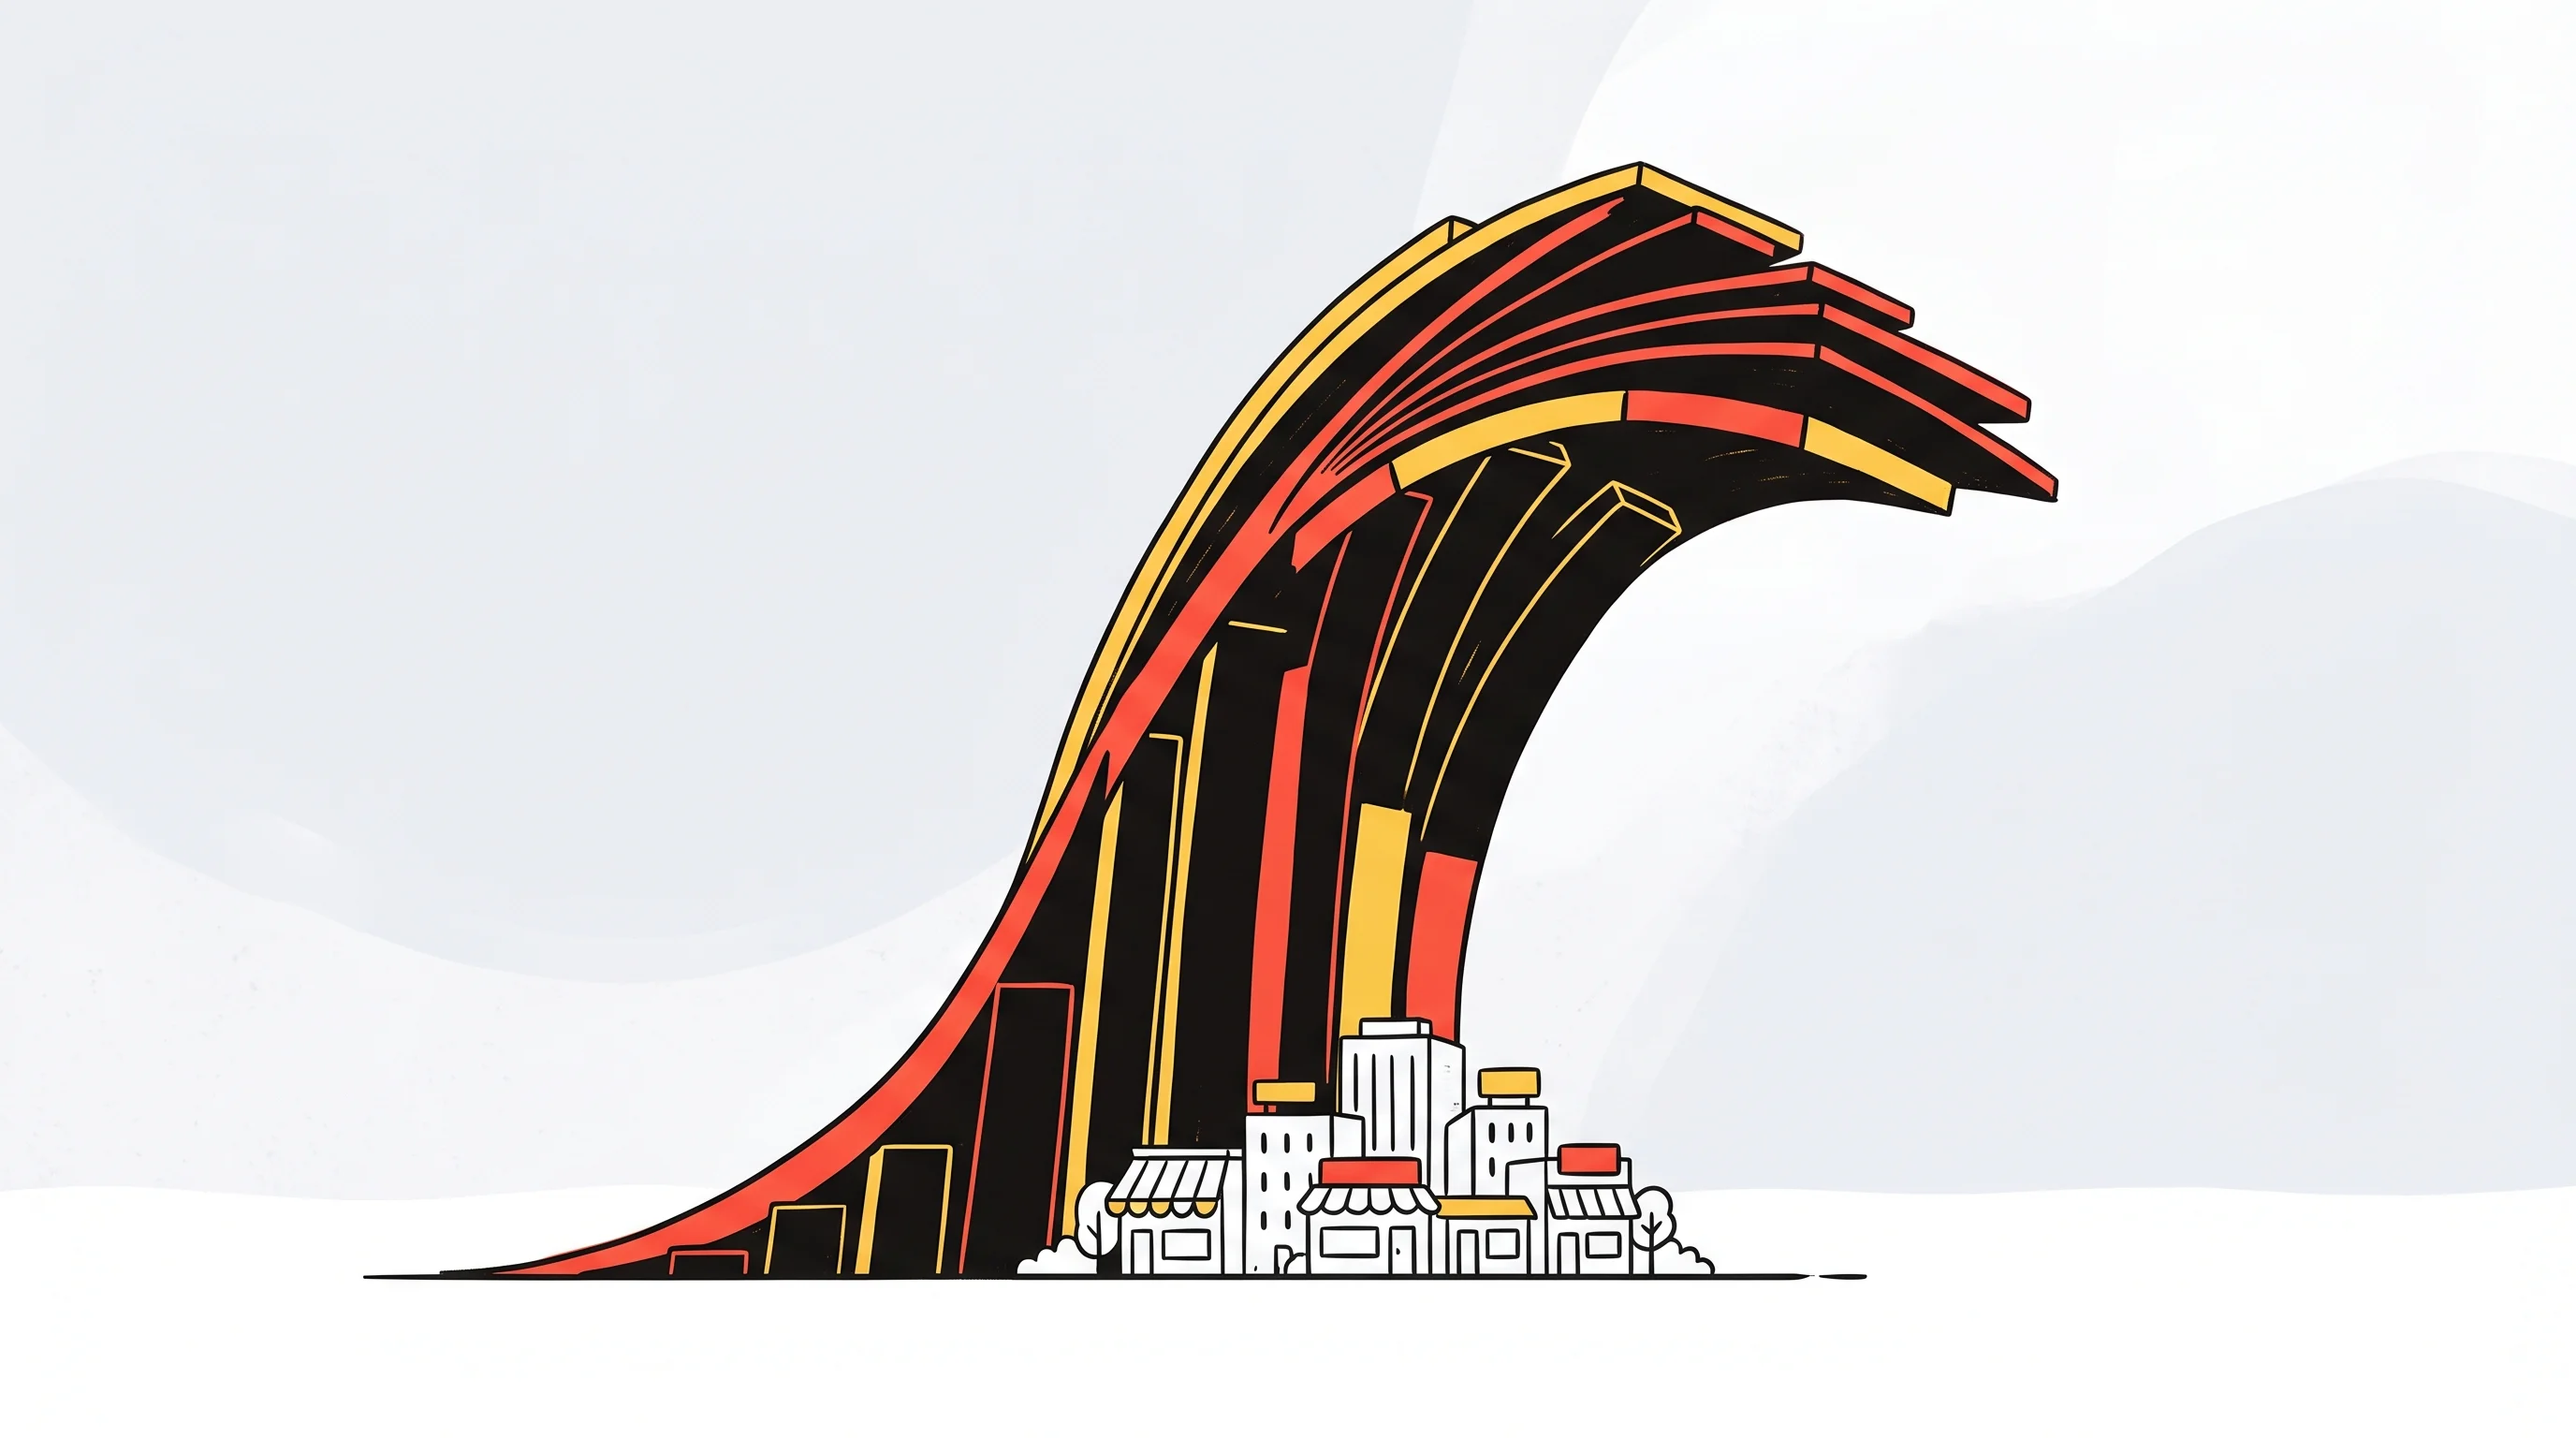
Look at the headline rounds. OpenAI's $122 billion raise in the first quarter reset all-time records and probably redefined what venture capital even means. Anthropic followed with a $30 billion Series G in February, then a $65 billion Series H in May, reaching a post-money valuation of $965 billion—a figure that would have seemed absurd for any private company just a few years ago. Elon Musk's xAI closed a $20 billion Series E in early January, with Tesla later disclosing a $2 billion investment. Waymo pulled in $16 billion. Jeff Bezos co-founded Prometheus—billed as building "an artificial general engineer for the physical world," whatever that means—and it raised $12 billion in June.
Even defense tech got in on the action: Anduril secured $5 billion at a $61 billion valuation in mid-May.
These aren't anomalies anymore. They're the new baseline, the water level everyone else is measuring against. China's DeepSeek reportedly closed a $7.4 billion first external round in June with an unusual governance structure that retains voting rights with a state AI fund—a detail that raised eyebrows among Western investors watching from the sidelines. The scale of these raises dwarfs entire seed markets. North America's second-quarter seed and angel total of $4.9 billion—covering thousands of companies, thousands of founders' hopes—wouldn't fund half of Anthropic's Series H.
Now contrast that with the experience on the ground for founders outside the AI mega-labs. Reach Capital's May assessment of the early-stage edtech landscape found fewer breakout companies, median round sizes holding within historical bands, but overall deal count down from 2025. Australia's second-quarter deal tally hit its slowest pace since before 2020, with the median journey from pre-seed to Series B stretching near 10 years, according to Cut Through Venture's quarterly report. India saw seed funding tick up 18% to $478 million in the first half—on 501 deals, a regional bright spot—but that's still rounding error compared to a single Silicon Valley mega-round.
The disconnect is visceral for founders navigating this environment. Carta's first-quarter data suggests seed median post-money valuations around $24.3 million over the prior six months, according to commentary published in July—higher than 2025, which sounds encouraging on paper. But medians mask distribution tails. Many founders still price well below the headline figures, and rising valuations can reflect selection bias: only the best-positioned companies are closing rounds at all. SSTI, citing PitchBook, noted U.S. seed-stage deal activity fell 33% from the fourth quarter of 2025 to the first quarter of 2026, signaling heightened selectivity among the investors still writing checks.
What Comes Next
The concentration is unlikely to reverse anytime soon. Perhaps that's the hardest part to accept. CB Insights' mid-year outlook anticipates continued high dollar totals with constrained breadth; AI mega-rounds and selective exits will keep driving headline numbers while new unicorn formation remains subdued. PitchBook's mid-year commentary flags persistent concentration, with exits improving but not broadly enough to normalize limited partner distributions across the ecosystem. BlackRock's 2026 Private Markets Outlook, published in January, highlighted the rise of secondaries and semi-liquid structures—innovations that recycle capital among existing stakeholders rather than flooding the seed stage with fresh checks.
For early-stage founders, this reality demands adaptation. Established seed firms continue to lead first checks, but many micro-VCs report longer fundraising timelines and smaller fund sizes. Accelerators remain a viable path—Y Combinator's standard $500,000 SAFE structure persists, though acceptance rates hover around 1–2%, making it more selective than most Ivy League schools. Angels and family offices are shifting tactics; the Angel Capital Association's 2026 report, published in June and July, notes governance involvement declining as round sizes swell, with angels increasingly organizing via syndicates and special purpose vehicles to pool capital.
Non-AI sectors face a steeper climb but aren't completely shut out. Fintech funding rose 23% year-over-year in the first half even as deal counts fell more than 25%, according to Crunchbase—another echo of the concentration theme playing out across categories. Enterprise software, according to Dealroom's live tracker through May, saw record flows but again clustered in large tickets to proven players. Defense and "physical AI" crossovers—think Anduril, think Prometheus—demonstrate that mega-rounds aren't exclusive to foundation models, but you need a credible path to strategic importance and massive scale to attract that kind of capital.
The New Playbook
The seed paradox of 2026—half a trillion dollars deployed while early deals starve—reflects a market in structural transition, not temporary correction. Capital is abundant in aggregate but inaccessible to most. The mega-funds and mega-rounds create a mirage of plenty while the earliest stages endure what one seed investor recently called "a quiet drought." No dramatic crash, no headlines about a bubble bursting. Just thousands of founders discovering that the money everyone keeps talking about isn't available to them.
If you're raising seed today, understand the field has tilted in ways that make the old playbooks less useful. The path isn't impossible—plenty of companies are still getting funded, still finding their footing—but it requires surgical precision. You need a problem aligned with where capital is actually flowing, not where you wish it would flow. You need traction that speaks louder than pitch decks, metrics that leave less room for debate. And you need the patience to outlast a market that rewards concentration over breadth, scale over experimentation.
The dollars are there, all half-trillion of them. Getting any meaningful portion to flow your way? That's become the hard part.


